Chicago Contractor Licensing Insurance: 2026 Requirements

Chicago contractor licensing insurance is the first thing the city checks, and it is the first thing that can sink an application. Illinois does not issue a statewide general contractor license. However, Chicago runs one of the most detailed licensing programs in the Midwest. Under Chapter 4-36 of the Municipal Code, general contractors hold a Class A through E license based on the size of the projects they take on.

In short, no insurance means no license. Below, we explain what the city expects, what changed in 2026, and how to avoid a costly lapse.

What Changed in 2026 for Chicago Contractor Licensing Insurance

On January 6, 2026, the Department of Buildings and its licensing partner, Continental Testing Services, updated the program. First, project limits for Class B, C, and D licenses doubled. Second, the general liability minimum for Class C and D licenses rose to $2 million per occurrence. Some older city summaries still show the previous $1 million figure, so always confirm the current number before you apply.

Also, fees rose for 2026 for the first time in years. As a result, a rejected application now costs you more time and more money.

Chicago Contractor Licensing Insurance Requirements by Class

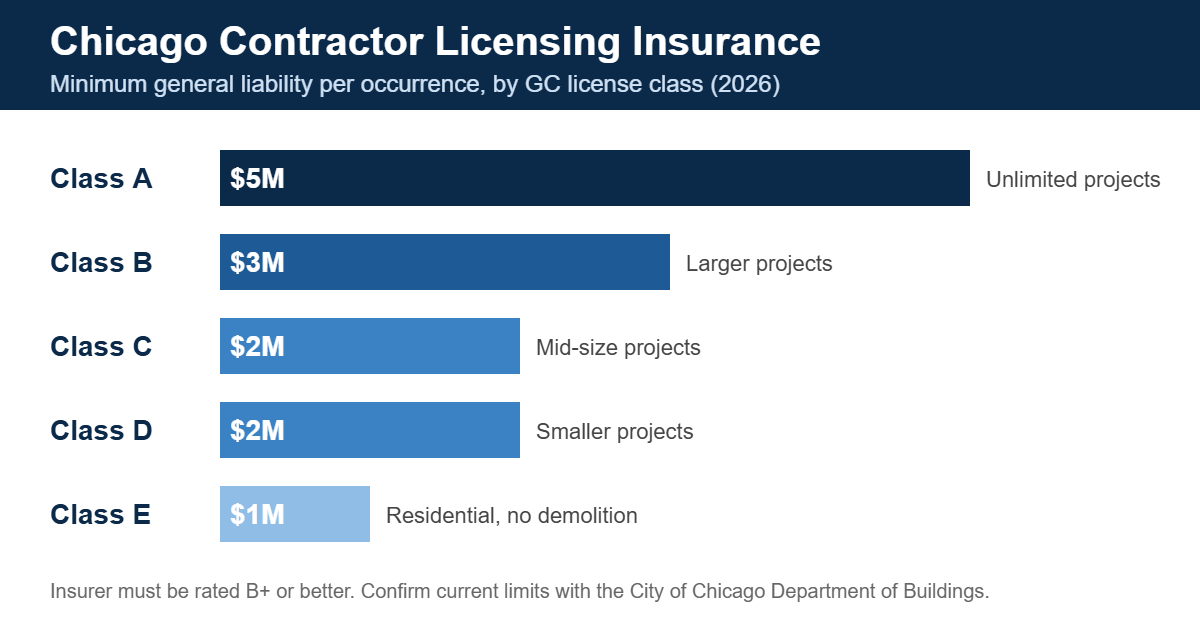
The higher your license class, the more coverage the city wants. The chart below shows the minimum general liability limit per occurrence for each class.

Chart of Chicago contractor licensing insurance minimums by general contractor license class
Minimum general liability per occurrence by Chicago GC license class. Confirm current limits with the city.

For example, a Class A contractor can bid on unlimited projects, but it needs $5 million per occurrence. Meanwhile, a Class E contractor works on smaller residential jobs with no demolition and needs $1 million. Class A and B limits can usually be met with a primary policy, an umbrella, or a combination of both.

What the City Looks for on Your Policy

Limits are only part of the picture for contractor licensing insurance in Chicago. In addition, the city reviews who issues the policy and how it is written.

  • Carrier rating: The insurer must be authorized in Illinois and rated B+ or better by A.M. Best.
  • Coverage scope: The commercial general liability policy should include bodily injury, property damage, and completed operations.
  • Additional insured status: Many project owners and general contractors also require the City of Chicago or the owner on the certificate. In that case, ask for primary and non-contributory wording.
  • Workers’ compensation: Illinois law generally requires it for contractors with employees. For details, see the Illinois Workers’ Compensation Commission.
  • Correct certificate: The certificate of insurance (COI) must match the program’s holder and notice wording.

Why a Lapse in Contractor Licensing Insurance Can Shut Down Jobs

The city ties your license to your policy, so Chicago contractor licensing insurance must stay active. Therefore, when the policy on file expires, the license becomes inactive automatically. Because permits depend on an active license, work on permitted jobs can stop until you fix it.

To prevent that, send renewal proof to Continental Testing Services before your policy expires. Then, keep a copy of every certificate you submit. Finally, calendar your policy renewal date 60 days ahead so your agent has time to issue new paperwork.

How to Get Your Chicago Contractor Licensing Insurance Ready

  1. Confirm which license class fits your largest planned projects.
  2. Compare your current limits with the 2026 minimums for that class.
  3. Add an umbrella policy if you need higher limits for Class A or B.
  4. Ask your agent for a certificate formatted for the Chicago program.
  5. Submit proof with your application, and again at every renewal.

For the official class table and application steps, review the City of Chicago general contractor license page.

Chicago Contractor Licensing Insurance FAQs

Does Illinois require a state general contractor license?

No. Illinois does not issue a statewide general contractor license. However, Chicago requires its own license for general contractors, and other cities set their own rules.

What happens if my insurance expires?

The city automatically inactivates the license when the policy on file expires. As a result, you may not be able to pull permits until you submit proof of renewed coverage.

Do I need an umbrella policy for a Chicago contractor license?

It depends on your class. For Class A and B, the city accepts the required limit through a primary policy or umbrella. Because umbrella coverage for Chicago contractor licensing insurance is often cheaper than raising the primary limit, many contractors use it.

Can my agent issue the certificate for the city?

Yes. Your agent can issue a certificate with the correct holder and wording. Still, send it early so any corrections do not delay your application.

Get Help With Chicago Contractor Licensing Insurance

Weer Insurance Group in Chicago, IL helps contractors line up general contractor insurance that meets city requirements. Our post on workers’ comp and auto for Chicago plumbers covers related coverage. Policy terms vary, so request a quote or call 773-545-2001 to review your limits before you apply or renew.

Read More

Builder’s Risk Insurance for Winter Construction in Chicago

Construction in Chicago doesn’t stop when temperatures drop. Framing, drywall, and concrete work often continue under tarps and plastic sheeting with temporary heaters running around the clock. However, that setup keeps a schedule on track, but it also concentrates several distinct risks in one partially finished building. Builder’s risk insurance can help with the build.

Matching Winter Risks to the Right Policy

Risk Coverage that usually responds What to confirm
Fire damaging the structure or stored materials Builder’s risk insurance Any heater or fire safety conditions written into the policy
Fire or smoke spreading to a neighboring property General liability Limits that fit a dense block with attached buildings
A worker overcome by carbon monoxide Workers’ compensation That every crew, including subs, carries their own coverage
Pipes freezing in an unfinished space Builder’s risk, depending on terms Whether the policy requires heat to be maintained

The Conditions Many Contractors Overlook

Some builder’s risk policies include protective safeguard requirements, such as keeping heaters attended, maintaining clearances from combustibles, or having extinguishers on each floor. These aren’t suggestions. Falling short of a written condition can complicate a claim, so it’s worth reading that section before the first cold snap.

A Short Cold-Weather Site Routine

  • Keep heaters clear of tarps, lumber, and insulation
  • Ventilate enclosed areas and use carbon monoxide detectors
  • Assign someone to check heaters at the end of each shift
  • Store propane cylinders according to the manufacturer’s and code guidance

Weer Insurance Group works with contractors across Chicago, from Portage Park to the collar counties, to line up general contractors’ insurance that fits year-round work. To review your builder’s risk insurance conditions before winter, stop by our Belmont Avenue office or reach out through Weer Insurance Group in Chicago, IL.

Read More

Chicago Contractor Liability Insurance: What You Really Need

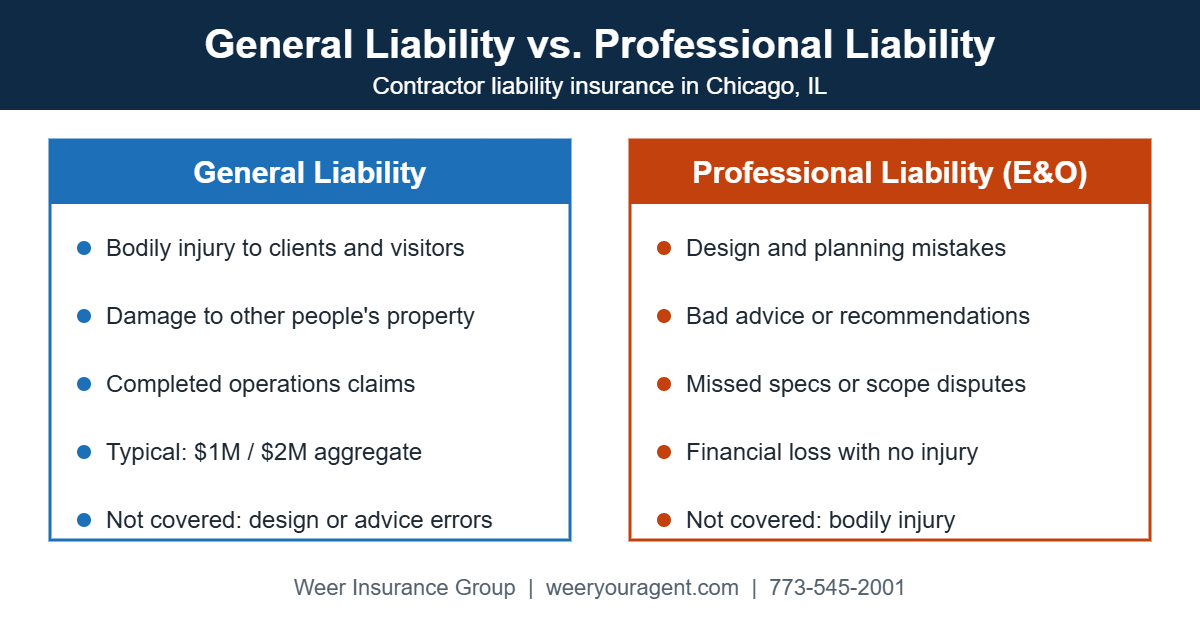
Quick answer: Most contractor liability insurance in Chicago starts with general liability, which covers injuries and property damage you cause to others. However, general liability does not cover mistakes in design, planning, or advice. If you give design input, recommend materials, or take on design-build work, you likely need professional liability too.

Chart comparing general liability and professional liability for contractor liability insurance in Chicago

What general liability covers for Chicago contractors

General liability is the policy every general contractor, owner, and property manager will ask to see on your certificate of insurance. It responds to physical harm and physical damage. For example:

  • A client trips over materials and gets hurt
  • A dropped tool injures someone nearby
  • A pipe you are working on bursts and floods the unit below
  • A ladder scratches a client’s hardwood floor

It also includes completed operations coverage. That protects you when damage shows up after a job is finished. Most Chicago contracts ask for $1 million per occurrence and $2 million aggregate.

What general liability does not cover matters just as much. It generally won’t pay to redo your own faulty work. It won’t cover injuries to your own employees, because that’s what workers’ compensation is for. And it won’t respond to claims about bad advice or design errors.

What professional liability covers

Professional liability, also called errors and omissions (E&O), covers claims tied to your judgment or advice rather than physical harm. Say you recommend a material or design approach that later fails. Or a client says the finished project doesn’t match the specs they believed you promised. Those are professional liability claims, not general liability ones.

General liability vs. professional liability at a glance

General liabilityProfessional liability
CoversBodily injury and property damage to othersFinancial loss from your advice, design, or planning errors
Typical claimA client trips over materials; a tool damages a floorA recommended design fails; a measurement error forces rework
Who asks for itAlmost every GC, owner, and property managerDesign-build owners, developers, and larger commercial clients
Common limits$1M per occurrence / $2M aggregateOften $1M per claim, set by contract

Real scenarios where the difference matters

  • A design-build contractor recommends a structural approach that later needs costly rework
  • A client claims a renovation didn’t match the agreed scope or specifications
  • A plan or measurement error forces a major correction
  • A client alleges financial loss from delays caused by planning mistakes, with no physical damage at all

In each case, no one was hurt and nothing was physically damaged. As a result, a general liability policy would likely deny the claim.

Who needs professional liability on top of general liability

Contractors who only perform labor to plans drawn by an architect or engineer may not need it. In contrast, you should consider professional liability if you:

  • Offer design-build services
  • Prepare drawings, layouts, or measurements that others rely on
  • Recommend specific materials, systems, or equipment
  • Manage projects or schedules for owners
  • Act as a construction manager or owner’s representative

This is increasingly common among Chicago contractors handling complex renovations and commercial build-outs.

Contractor liability insurance requirements in Illinois

Illinois does not set one statewide general liability requirement for every contractor. Instead, the requirements usually come from three places. First, local licensing: the City of Chicago, for example, requires licensed general contractors to show proof of liability insurance. Second, your contracts, which often spell out limits, additional insured status, and a waiver of subrogation. Third, state law for employees, since the Illinois Workers’ Compensation Act requires coverage for nearly every employer.

So before you bid, read the insurance section of the contract. Then make sure your contractor liability insurance in Chicago actually matches it.

What contractor liability insurance costs in Chicago

Cost depends on your trade, revenue, payroll, claims history, and the type of work you do. A small remodeling crew and a commercial design-build firm will pay very different amounts. Professional liability is usually priced separately, based on your design revenue and the size of your projects. The best way to know your number is to have an agent quote both policies side by side.

Frequently asked questions

What liability insurance does a contractor need in Illinois?

Most contractors carry general liability, commercial auto, and workers’ comp if they have employees. Contractors who give design input or advice should add professional liability. Your contracts and local licensing rules set the minimum limits.

Does general liability cover faulty workmanship?

Generally, no. General liability usually won’t pay to fix your own work. However, it can cover damage your faulty work causes to other property, such as water damage from a failed pipe.

Is professional liability the same as E&O insurance?

Yes. Professional liability and errors and omissions (E&O) are two names for the same type of coverage.

Does general liability cover injuries to my own workers?

No. Injuries to your employees fall under workers’ compensation. General liability covers bodily injury to third parties, such as clients, visitors, or other trades on site.

How much liability coverage do Chicago contractors usually carry?

Most carry $1 million per occurrence and $2 million aggregate in general liability. Many commercial contracts also require an umbrella of $2 million to $5 million or more on top.

Get your contractor liability insurance in Chicago reviewed

Weer Insurance Group helps Chicago contractors decide whether their work calls for professional liability alongside general liability and workers’ comp. As an independent agency, we can quote both from multiple carriers. Request a quote, visit our general contractor insurance page, or call 773-545-2001.

Related reading: contractor insurance requirements in the Chicago Loop, Chicago roofing contractor insurance, and builder’s risk insurance for winter construction.

Read More

Chicago’s Historic Building Conversions Complicate Condo Insurance

Condo Insurance for When a Century-Old Building Becomes a Condo


Chicago is full of converted historic buildings, old factories, warehouses, and apartment blocks turned into condominiums that carry decades of character. These conversions give owners a unique kind of home, but they also create insurance considerations that newer construction simply doesn’t face. Weer Insurance Group works with associations and historic buildings across Chicago that are often surprised by how differently these buildings need to be evaluated for condo insurance.


Replacement Cost Gets Complicated Fast


Rebuilding a converted historic structure to current code can cost significantly more than replacing a modern building of the same size. Original masonry, ornamental details, and non-standard layouts often require specialized labor and materials that are harder to source and more expensive to replicate. A master policy based on outdated replacement figures can leave an association seriously

under insured

after a major loss.


Code Compliance Adds Another Layer


Buildings converted decades ago were often grandfathered under older codes when they first became residential. If a significant loss requires substantial rebuilding, current building and fire codes typically apply to the reconstruction, even if the original structure never had to meet them. This can mean unexpected costs for updated electrical systems, fire suppression, or structural reinforcement that weren’t part of the original conversion.


Unique Architectural Features Carry Their Own Risk


    • Original wood beams, exposed brick, or cast iron elements may be difficult or impossible to match after damage


    • Older plumbing and electrical systems can increase the likelihood of certain types of claims


    • Irregular unit layouts from conversion can complicate how coverage is divided among owners


Why Regular Condo Insurance Reviews Matter More Here


Because construction costs and code requirements keep shifting, a converted building’s insurance needs can change more quickly than boards expect. Associations that assume their coverage from years ago still reflects reality often discover otherwise only after a claim. For more on how underinsurance tends to surface at renewal, take a look at our related piece on condo insurance mistakes Illinois boards make at renewal.


Historic conversions give Chicago condo buildings their character, but that character comes with insurance considerations that deserve regular attention. Weer Insurance Group helps associations throughout Chicago review their coverage against the realities of older, converted structures. To learn more, visit our condo associations page.

Related reading: Illinois condo D&O insurance: is your board personally exposed? and why liability coverage matters for Chicago condo owners. Unit owners can also see our condo insurance page.

Read More

Why Liability Coverage Is Crucial for Chicago Condo Owners

Liability Risks Are Common in Chicago Condo Living

Condo living in Chicago offers convenience and access to vibrant neighborhoods, but it also comes with shared spaces and close proximity to neighbors. These factors increase the chance of liability-related incidents that can extend beyond your own unit. Liability coverage within a condo insurance policy helps protect unit owners when they are held responsible for bodily injury or property damage involving others.

At Weer Insurance Group in Chicago, Illinois, conversations with condo owners often reveal misunderstandings about how much protection an association’s master policy actually provides. While the HOA policy covers common areas and certain building elements, it typically does not protect individual owners from personal liability claims.

Everyday Scenarios Where Liability Coverage Applies

Liability issues do not always stem from major accidents. Water damage from a leaking appliance, a guest slipping inside your unit, or damage caused during renovations can all trigger liability claims. In multi-unit Chicago buildings, even minor incidents can affect neighboring condos and lead to complex responsibility questions.

Personal liability coverage helps address legal defense costs and covered damages when a condo owner is found responsible. Without it, these expenses may need to be paid out of pocket.

Why Chicago Condo Owners Face Elevated Liability Exposure

  • Shared walls, plumbing, and electrical systems
  • Frequent guests, deliveries, and service providers
  • High-density living with limited separation between units

These factors make liability coverage a core component of a well-rounded condo insurance policy rather than an optional add-on.

How Liability Coverage Complements Other Condo Protections

Liability coverage works alongside personal property and interior coverage to form a complete insurance approach. While property coverage focuses on belongings and interior features, liability coverage focuses on protecting financial stability when claims involve other people.

Condo owners working with Weer Insurance Group in Chicago, Illinois benefit from guidance that reflects the realities of urban condo ownership. To learn more about condo insurance and liability protection, visit the Weer Insurance Group website or explore their condo insurance resources.

Read More

Do Delivery Drivers Need Commercial Auto Insurance?

Food delivery is one of the most popular side hustles in Chicago. But here’s the catch: your personal auto policy probably won’t cover you while you deliver. So if you crash with a DoorDash bag in your car, your insurer can deny the claim. As a result, you could be stuck paying for car damage, medical bills, and even lawsuits.

The right coverage depends on a few things. What do you deliver? How often do you drive? And which platform do you work for? Here’s how the coverage really works, and where the gaps are.

Why Your Personal Auto Policy Won’t Cover Deliveries

Almost every personal auto policy in Illinois has a “business use” exclusion. In plain English, your coverage can stop the moment you use your car to earn money. That even includes the drive to the restaurant to pick up an order.

Why do insurers care? Because delivery driving is riskier. You spend more time on the road. You make more stops. Plus, you often drive under time pressure. So if an adjuster learns the crash happened during a delivery, they will likely deny the claim. The Insurance Information Institute has a clear guide on how these gaps work for app-based drivers.

And the cost of a denied claim is real. You could pay for the other driver’s car and injuries out of pocket. You might also pay for your own repairs. On top of that, your insurer may drop you afterward.

What DoorDash, Uber Eats, and Grubhub Actually Cover

Most delivery apps advertise insurance for their drivers. However, the coverage is thinner than most drivers think. For example, DoorDash’s coverage generally applies only during an active delivery. It also acts as “excess” coverage in most cases. That means it only pays after your own policy responds — or denies the claim.

In short, there are three coverage periods to know:

  1. App on, waiting for an order — usually little or no app coverage
  2. Order accepted, driving to pick up — partial app coverage at best
  3. Food in your car, headed to the customer — the app’s strongest coverage window

See the problem? Your personal policy excludes business use in all three periods. Meanwhile, the app only steps in during the last one. Even then, it often won’t pay for damage to your own car. Every app’s terms are different, so read them closely. Better yet, let an agent read them with you. Our commercial auto insurance team reviews these terms for Chicago drivers all the time.

Independent Contractors: You’re On Your Own for Coverage

Maybe you don’t drive for the big food apps. Instead, you deliver equipment, retail goods, medical supplies, or auto parts as an independent contractor. In that case, there is no app policy behind you at all. The coverage is fully your job.

So be upfront with your agent about how you use your car. What do you haul? How many work miles do you drive? Do you travel between stores or job sites? These details decide what you need. It might be a simple business-use add-on to your personal policy. Or it might be a true commercial auto policy. Guess wrong either way and it costs you. One way leaves you exposed. The other way, you overpay for coverage you don’t need.

Also, many clients require proof of commercial coverage before you can start work. They ask for a certificate of insurance. If you’re building your own delivery business, talk this through before you sign a contract. Our business insurance team can show you what those contracts usually require.

Pizza Delivery Drivers Face the Strictest Rules

Insurers treat pizza delivery as one of the riskiest jobs in personal auto. Why? Fast delivery windows, frequent trips, night driving, and busy city streets. Most pizza shops don’t provide cars or insurance either. In fact, many insurers simply exclude pizza delivery from personal policies altogether.

So if you deliver pizza in Chicago, don’t assume you’re covered. And don’t assume your employer has you protected. Ask your insurer directly — in writing if you can. The Illinois Department of Insurance also publishes a consumer guide on required auto coverage in the state. Keep in mind, those state minimums can run out fast in a serious delivery crash.

How to Close the Gap: Your Options in Illinois

The good news? The fix is usually one of three things:

  • Rideshare or delivery endorsement. This add-on covers the “app on” gap. It’s the cheapest option for part-time drivers. However, not every carrier offers it for food delivery.
  • Commercial auto policy. This is full business coverage for your vehicle. Most full-time drivers and contractors need this one.
  • Hybrid gig-driver policies. Some carriers now blend personal and business coverage in one policy.

The right choice depends on your platform, your hours, and your vehicle. But the wrong choice is doing nothing and hoping no one checks.

Talk to a Chicago Agency That Knows Delivery Risk

At Weer Insurance Group, we help delivery drivers, couriers, and contractors across Chicago every week. Because we’re independent, we can shop carriers that actually want delivery business. Many captive agents can’t quote these at all. We’ll review your current policy and read your app’s coverage terms. Then we’ll tell you honestly what you need — an endorsement or a commercial policy. We serve Chicago, the suburbs, and all of Illinois, Wisconsin, and Indiana. Plus, we speak English, Spanish, Polish, Ukrainian, and Russian.

Contact us today for a free coverage review. Do it before your next shift — not after your first denied claim.


Frequently Asked Questions

Does DoorDash provide insurance for its drivers? Yes, but it’s limited. The coverage mainly applies during active deliveries. Also, it usually pays only after your own policy responds first. And it typically won’t cover damage to your own car.

Will my insurance company find out I do deliveries? Often, yes. Adjusters investigate how a crash happened. So if you were delivering, they can deny the claim. They may also drop your policy afterward.

How much does commercial auto insurance cost for delivery drivers in Chicago? It depends on your car, your record, and your delivery type. A delivery endorsement can cost a few hundred dollars a year. A full commercial policy costs more. Still, both cost far less than one uncovered crash.

Do I need commercial insurance if I only deliver part-time? Maybe not a full policy. But you likely need at least a delivery endorsement. Even one delivery a week can trigger the business-use exclusion.

Read More