Restaurant Group Insurance: One Program for Every Location

Restaurant group insurance is the coverage plan that protects every location you own under one roof. When it is built well, each site has the right limits and every policy renews on the same day. When it grows one store at a time, gaps creep in. As a result, a single claim can hurt the whole group.

This guide is for owners of multi-location restaurant groups in Illinois, Wisconsin and Indiana. If you run three to fifteen units, you likely have several leases, liquor licenses and payrolls. So here is how strong groups set up their programs. We also show where the gaps usually hide.
Restaurant group insurance for a multi-location Illinois restaurant owner

Why Restaurant Group Insurance Gets Messy

Most groups don’t plan their insurance. Instead, it piles up. The first store gets a package policy. Then the second store gets its own policy, often from a different agent. Later, a third site opens with a rushed quote to meet a lease deadline.

Soon you have five renewal dates, three carriers and limits that don’t match. In addition, each policy may define “location” or “premises” a little differently. That makes claims harder and certificates slower.

Underwriters notice this too. A scattered program looks harder to manage. On the other hand, a clean schedule of locations with matched limits shows control. Therefore, more carriers may compete for your account.

The Core of Restaurant Group Insurance: One Package

Most groups do best with one package policy that lists every location. A typical package combines general liability, property and business income. Many carriers also write liquor, umbrella and workers’ comp on the same account.

One package has clear benefits:

  • One renewal date for the whole group
  • One set of limits that you can match to your strictest lease
  • One claims team that already knows your business
  • Blanket property limits that can float between sites
  • Simpler certificates for landlords, lenders and event clients

Still, one package is not always possible. A high-liquor location may need a specialty market. In that case, keep the rest of the group together and match limits on the odd one out.

Per-Location Limits Protect the Whole Group

Here is a gap many owners miss. A general liability policy has a yearly aggregate limit. That is the most it will pay for all claims in a policy year. Without an endorsement, every location shares that one aggregate.

So a bad year at one store can drain coverage for the rest. A per-location aggregate endorsement fixes this. It gives each listed site its own aggregate limit. The standard form is the CG 25 04. (Insureon)

Also, many landlords now ask for it in the lease. Therefore, check that every location is on the schedule. A new store left off the list may not get its own limit.

Liquor Liability Across Every License

If your group serves alcohol, liquor liability is often your largest exposure. Under the Illinois Dram Shop Act, a business that serves someone who later causes harm can be sued. (235 ILCS 5/6-21)

Illinois caps those damages. For claims settled on or after January 20, 2026, the cap is $90,411.55 per person for injury or property damage. The cap for loss of support or society is $110,503. (Illinois Comptroller) However, those caps apply to each injured person. In other words, one crash can mean several claims.

Each license also has its own rules. For example, Chicago requires at least $300,000 per occurrence in liquor liability. The Local Liquor Control Commissioner must be the certificate holder, with 30 days’ notice of cancellation. (City of Chicago) Suburbs set their own minimums. So list every license and its rule in one place.

Finally, check two things. First, is liquor on your umbrella’s schedule of underlying policies? Second, is assault and battery covered, or cut to a small sublimit? For more, see our guide to Illinois liquor liability.

Property, Spoilage and Business Income

A kitchen fire, a burst pipe or a power outage can close a store for weeks. Meanwhile, rent, payroll and loan payments keep coming. That is why property and business income are core parts of restaurant group insurance.

Strong programs often include:

  • Blanket property limits across locations, so one site can draw on more if needed
  • Equipment breakdown for walk-ins, hoods, fryers and HVAC
  • Food spoilage after a power outage or cooler failure
  • Business income with enough months to reopen and rebuild sales
  • Utility service interruption, since many outages start off your premises

Next, review your business income worksheet each year. Sales grow when you add units. However, many groups never update the limit. As a result, they may be underinsured when a claim hits. Learn more on our commercial property insurance page.

Workers’ Comp for a Growing Team

Restaurant groups run on people. Cuts, burns and slips are common kitchen injuries. So workers’ comp is often one of the biggest premiums in restaurant group insurance.

In Illinois, even one part-time employee means you must carry it. Employers who knowingly skip coverage face fines of up to $500 a day, with a $10,000 minimum. The state can also order you to stop work. (Illinois Workers’ Compensation Commission)

Also, keep payroll split by location and job type. Front-of-house, kitchen and office staff often rate differently. Clean records make your year-end audit faster and fairer. For more, see our workers’ compensation page.

Employment and Privacy Risks for Restaurant Groups

As headcount grows, so do employee claims. Wage, harassment and wrongful firing claims are common in hospitality. Therefore, many groups add employment practices liability, often called EPLI, to their restaurant group insurance.

Illinois adds one more risk. The Biometric Information Privacy Act covers fingerprint time clocks. In 2023, the Illinois Supreme Court ruled that each scan could count as a separate violation. In August 2024, the law was amended. Now repeat scans of the same person by the same method count as one violation. (Duane Morris)

Still, damages can reach $1,000 or $5,000 per person. So if you use finger scans, get written consent from every worker. Also, ask whether your EPLI or cyber policy covers biometric claims. Many policies exclude them.

Auto Risk From Catering and Delivery

Many groups now cater or deliver. Often, staff drive their own cars. If a driver causes a crash on a work run, the injured person may sue your business too.

Hired and non-owned auto coverage helps here. It covers your business when staff use rented or personal vehicles for work. Also, if you own a catering van, it needs a commercial auto policy. See our commercial auto insurance page for details.

How to Prepare for Your Restaurant Group Insurance Renewal

Carriers that want restaurant groups look closely at how you run each store. So start 60 to 90 days before renewal. Then gather:

  1. A list of every location, with square footage and seats
  2. Food and alcohol sales by location
  3. Hours, live music and any late-night service
  4. Payroll by location and job type
  5. Every lease’s insurance section
  6. Every liquor license and its minimum limit
  7. Five years of loss runs on every line
  8. Your BASSET training records

As a result, carriers can quote faster and with fewer guesses. A complete file often means better terms. For neighborhood examples, see our Wicker Park bar insurance page.

Restaurant Group Insurance FAQ

Should every location be on one policy?

Often, yes. One package can mean one renewal and matched limits. However, a high-liquor site may need its own policy. In that case, line up its dates and limits with the rest.

What is a per-location aggregate?

It is an endorsement that gives each listed location its own yearly limit. So a big claim at one store doesn’t use up coverage for the others.

How much umbrella should a restaurant group carry?

It depends on your leases, licenses and sales. Many groups carry several million dollars. Also, make sure the umbrella sits over your liquor policy.

Does general liability cover a drunk-driving claim?

Usually not, if you sell or serve alcohol. Most general liability forms exclude liquor. Instead, you need liquor liability coverage.

When should we start our renewal?

Start 60 to 90 days out. That gives carriers time to review your locations and loss runs.

Get a Restaurant Group Insurance Review

If your group has added locations, your program should keep up. We can review your package, liquor, umbrella and workers’ comp in one meeting. Then we will show you where the gaps are. Request a commercial quote or call Weer Insurance Group at 773-545-2001. You can also learn more on our bars and restaurants insurance page.
Read More

Construction Workers Compensation: Year-End FAQ for Contractors

Construction workers compensation is often the largest premium on a contractor’s account. It is also the line most likely to surprise you after the policy ends. With year-end audits and January 1 renewals coming up, now is a good time to check it.

This FAQ is for owners of growing contractors with several crews. We answer the questions we hear most about mods, audits and class codes.

Construction workers compensation for a growing Illinois contractor

Who Needs Construction Workers Compensation in Illinois?

Nearly every employer does. In Illinois, even one part-time employee triggers the rule. Also, coverage must start on day one. (Illinois Workers’ Compensation Commission)

Construction gets extra attention. Some owners and LLC members may opt out in other fields. However, construction and other extra-hazardous firms generally must carry coverage. Employers who knowingly go without it face fines of up to $500 a day, with a $10,000 minimum. In addition, the state can issue a stop-work order.

How Does the Experience Mod Affect Construction Workers Compensation?

Your experience mod compares your losses to similar employers. A mod of 1.00 is average. Below 1.00 is a credit, which lowers your premium. Above 1.00 is a debit, which raises it. (NCCI)

The mod usually uses three years of payroll and losses. It skips the current policy. So a claim this year can affect your price for years.

Small claims affect construction workers compensation costs more than many owners think. The formula weighs how often you have claims more than how big they are. In other words, many small claims can hurt more than one large one. On the other hand, medical-only claims count at just 30%. So report injuries fast, and get workers care early.

Also, a high mod can cost you work. Some owners won’t let you bid with a mod above 1.00. Even so, NCCI says the mod was built to price premium, not to rank safety. (NCCI)

Why Did My Construction Workers Compensation Audit Go Up?

Your construction workers compensation premium starts as an estimate. After the term ends, the carrier audits your actual payroll. Then it bills or refunds the difference.

Audits usually jump for three reasons:

  1. Payroll grew. You added crews or gave raises during the year.
  2. Uninsured subs. If a sub had no comp, the auditor may add their pay to yours.
  3. Wrong class codes. Office staff landed in field codes, or the other way around.

Therefore, keep your records clean all year. Track sub certificates, split payroll by class and keep overtime records. Under NCCI rules, the extra “half” of time-and-a-half can often be left out if your records show it.

What Are the Classification Traps?

In construction workers compensation, class codes set your rate per $100 of payroll. Roofing and steel codes cost far more than carpentry or office codes. So one misplaced worker can swing your bill.

The most common traps include:

  • Putting a field supervisor in a clerical code
  • Splitting one worker’s pay across codes without records to back it up
  • Treating crew members as 1099 contractors

That last one is costly in Illinois. The Employee Classification Act presumes construction workers are employees. To call someone independent, a contractor must meet a three-part test. Penalties can reach $1,500 per violation. Also, each day can count as a new violation. (Illinois Department of Labor)

How Can Contractors Lower Construction Workers Compensation Costs?

There is no single fix. However, these steps often help:

  • Write a safety program, and put one person in charge
  • Offer light-duty work so injured workers return sooner
  • Report every injury to your carrier the same day
  • Collect comp certificates from every sub before work starts
  • Review class codes with your agent before each renewal
  • Use the carrier’s safety services, which are often free

Next, think about the market. Some carriers write comp as part of a whole-account package with general liability, auto and umbrella. Others focus on comp for skilled trades. As an independent agency, we can compare both. Learn more on our workers’ compensation page. Also see how comp fits a full general contractors insurance program.

A Year-End Construction Workers Compensation Checklist

Before December 31, set aside 30 minutes with your office manager. Then work through this list:

  1. Pull current comp certificates for every sub you paid this year
  2. Flag any sub whose policy lapsed during a job
  3. Check that each worker sits in the right class code
  4. Total overtime pay apart from regular pay
  5. Get your loss runs and your new mod worksheet
  6. Tell your agent about any payroll growth now

As a result, your audit goes faster. You also walk into renewal with fewer surprises.

More Construction Workers Compensation Questions

When does a new experience mod take effect?

Usually on your policy’s renewal date. So ask for your mod worksheet before renewal and check it for errors.

Can I exclude myself as the owner?

Sometimes. Illinois lets some owners and officers opt out. However, construction firms face stricter rules, so ask first.

Do I need comp for 1099 workers?

Often, yes. Illinois presumes construction workers are employees unless all three tests are met. Otherwise, your carrier may charge for them at audit.

What should I bring to my audit?

Bring payroll by class, overtime records, sub certificates and sub payments. Also bring your quarterly payroll tax forms.

Should my comp be with the same carrier as my liability?

Often, it helps. One carrier for the whole account can mean one renewal and one claims team. Still, a comp specialist may fit high-hazard trades better. So compare both at renewal.

Get a Construction Workers Compensation Review

Year-end is the best time to fix class codes and sub files. We can review your mod, your last audit and your renewal in one meeting. Request a commercial quote or call Weer Insurance Group at 773-545-2001.

Read More

Subcontractor Risk Transfer: How GCs Protect Their Program

Subcontractor risk transfer is how a general contractor moves job risk onto the subs who create it. When it works, a sub’s mistake lands on the sub’s policy. When it fails, the claim lands on yours. As a result, your loss runs, your premium and even your next bid can take the hit.

This guide is for owners of multi-crew general contractors and construction managers. If you run $5 million to $50 million of work a year, your subs likely do most of it. So here is how strong firms set up contracts, certificates and endorsements. We also show where the gaps usually hide.

Subcontractor risk transfer for a Chicago general contractor

What Subcontractor Risk Transfer Means

Risk transfer uses three tools. First, the subcontract, with its indemnity clause. Second, insurance rules, such as additional insured status. Third, a tracking system that proves each sub actually complied.

Each tool backs up the others. For example, an indemnity clause is only as good as the sub’s ability to pay. By contrast, additional insured status gives you direct rights under the sub’s policy. In other words, you become an insured on their policy, not just a name in a contract.

Underwriters notice this. Carriers that write mid-size contractors often ask how you manage subs before they quote. So a clean process can mean better terms at renewal.

Start With a Written Subcontract

Subcontractor risk transfer starts with paper. Many additional insured endorsements only respond when a written contract requires them. For example, the blanket form CG 20 33 needs a written deal between your sub and you. Without one, you may have no coverage at all. (Insurance Journal)

So sign the subcontract before the sub sets foot on site. Don’t wait for the first pay app. Also, use the same core terms on every job. Then review them each year with your attorney.

A strong subcontract usually spells out:

  • Required coverages and minimum limits
  • Additional insured status for ongoing and completed work
  • Primary and non-contributory wording
  • A waiver of subrogation on each line
  • How long completed operations coverage must stay in place
  • Who must be named: you, the owner, the lender and others the prime contract lists

Illinois Rules That Shape Subcontractor Risk Transfer

Illinois adds a twist. Its Construction Contract Indemnification for Negligence Act voids any promise to indemnify someone for their own negligence. (740 ILCS 35/1) In other words, the indemnity clause can’t make a sub pay for your own mistakes.

However, the Act does not apply to insurance contracts or agreements. (Taft Law) That is why additional insured status carries so much weight here. Still, courts can void an insurance clause tied too closely to a bad indemnity clause. Therefore, keep the two clauses separate.

There is one more wrinkle, called the Kotecki cap. Say a sub’s worker is hurt and sues you. You can then seek contribution from the sub. But that amount is usually capped at the sub’s workers’ comp benefits. Some subcontracts ask the sub to waive that cap. Ask your attorney whether that fits your contracts.

Additional Insured Endorsements for Ongoing and Completed Work

The certificate is not the coverage. The endorsement is.

Most construction programs use two ISO forms. The CG 20 10 covers you during the sub’s ongoing work. The CG 20 37 covers you after the work is done. Older CG 20 10 editions covered both. Newer ones only cover ongoing work. (Insurance Journal) As a result, a sub with only a CG 20 10 can leave you exposed once they leave the site.

That gap matters. Many defect claims show up years after a job closes. So require completed operations coverage. Also require it for a set number of years after the job ends.

Next, watch the blanket forms. The CG 20 38 can extend coverage up the chain to the owner and others your contract names. However, many carriers use their own versions. So read the actual wording.

Primary Wording and Waiver of Subrogation

Additional insured status is only one part of subcontractor risk transfer. Next, ask whose policy pays first.

Primary and non-contributory wording means the sub’s policy responds before yours. It also keeps the sub’s carrier from asking yours to share. Without it, the two carriers may split the loss. Consequently, your loss runs still take a hit.

A waiver of subrogation stops the sub’s carrier from suing you after it pays a claim. Ask for it on every line, including workers’ comp. In addition, check that the sub’s umbrella follows the same terms. Some umbrellas only extend coverage when the contract requires it.

Certificates Are Not Enough

A certificate of insurance is a snapshot. It shows a policy existed on the day it was issued. However, it does not change the policy. In fact, it may not even show which endorsements are attached.

So collect more than the certificate. Strong GCs ask for:

  1. The certificate, with your firm and the owner named correctly
  2. Copies of the additional insured endorsements
  3. The primary and waiver endorsements
  4. Proof of workers’ comp, or a valid exemption
  5. Umbrella certificates when the contract calls for them

Then track expiration dates. A policy that lapses mid-job leaves you open. Many firms now use software or a service to chase renewals. Either way, one person in your office should own the process.

Uninsured Subs and Your Workers’ Comp Audit

Here is a cost many GCs miss. If a sub has no workers’ comp, your carrier may treat their crew as yours at audit. As a result, you pay comp premium on their payroll.

Illinois also presumes that people doing construction work are employees. Under the Employee Classification Act, a contractor must meet a three-part test to treat someone as independent. Penalties can reach $1,500 per violation, and each day can count separately. (Illinois Department of Labor)

Therefore, make comp certificates part of your subcontractor risk transfer process. Collect one from every sub, every year. Also, be careful with one-person subs who claim an exemption. Ask your agent before you accept one. For more, see our workers’ compensation page.

Matching Sub Limits to the Job

Not every sub needs the same limits. A painter on a small tenant job is not a crane crew on a mid-rise. So build tiers into your subcontractor risk transfer rules.

For example, many GCs use three levels:

  • Low-hazard trades: $1 million per occurrence and $2 million aggregate
  • Mid-hazard trades: the same, plus an umbrella of a few million
  • High-hazard trades like roofing, steel and excavation: higher umbrella limits, often $5 million or more

Next, match your tiers to your own contracts. If an owner wants $10 million from you, your biggest subs may need more too. For Chicago license limits, see our guide to Chicago contractor licensing insurance.

How Subcontractor Risk Transfer Affects Your Premium

Your own general liability is often rated on payroll, sales or subcontracted costs. Also, many carriers charge more for subs who are uninsured or underinsured. In other words, a sloppy file can raise your rate.

On the other hand, a strong program helps. Signed contracts, endorsements and a tracking log show underwriters less risk. As a result, more carriers may compete for your account. For the full picture, see our general contractors insurance page. You can also review the basics of general liability insurance.

Subcontractor Risk Transfer FAQ

Is a certificate of insurance enough to protect my firm?

Usually not. A certificate only summarizes a policy. So ask for the actual additional insured, primary and waiver endorsements too.

Can I require Illinois subs to name me as additional insured?

In general, yes. The state’s anti-indemnity law voids clauses that make a sub pay for your own negligence. However, it does not apply to insurance agreements. Still, have your attorney review the wording.

How long should completed operations coverage last?

Many GCs require it for several years after the job closes. Match it to your warranty and to how long defect claims can be filed. Your attorney can set the right number.

What happens if a sub has no workers’ comp?

Your carrier may charge you for their payroll at audit. You could also face a claim if their worker is hurt. So collect a comp certificate before work starts.

Should every sub carry the same limits?

No. Many GCs set limits by trade hazard and job size. As a rule, high-hazard trades carry more.

Get a Subcontractor Risk Transfer Review

If your firm has grown, your sub requirements should grow with it. We can review your subcontract, your certificate process and your own program in one meeting. Then we will show you where the gaps are. Request a commercial quote or call Weer Insurance Group at 773-545-2001.

Read More

Illinois Liquor Liability: What Bar Owners Must Carry

Illinois liquor liability is one of the biggest risks a bar or restaurant group faces. One over-served guest can lead to a car crash, a fight or a lawsuit. Under the Illinois Dram Shop Act, your business can pay for harm that guest causes. As a result, the right coverage matters as much as your liquor license.

This guide is for owners of taverns, sports bars and multi-location restaurant groups. We insure hospitality businesses across Illinois, Wisconsin and Indiana. Here is what the law says, what you need to carry and where coverage often falls short.

Illinois liquor liability insurance for a Chicago bar and restaurant group

How the Illinois Dram Shop Act Works

The Dram Shop Act is part of the state’s Liquor Control Act. It lets an injured person sue a licensed business whose alcohol sales helped make someone drunk. (235 ILCS 5/6-21)

In other words, a guest drinks at your bar, drives away and hits someone. The injured driver can then bring a claim against your business. Also, the law reaches further than many owners expect. For example, a landlord who knowingly lets alcohol be sold on the property can share the blame.

Still, the law has limits. The drunk guest cannot sue you under the Act for their own injuries. In addition, a claim must be filed within one year.

2026 Illinois Liquor Liability Limits

Illinois caps dram shop damages. The caps change each year with inflation, and the State Comptroller sets them every January 20. For judgments or settlements on or after January 20, 2026, the limits are:

  • $90,411.55 per person for injury to a person or property
  • $110,503.00 for loss of means of support or loss of society

(Source: Illinois Comptroller)

These caps may sound low. However, they apply to each injured person, not each incident. So one crash with four injured people can mean four claims. On top of that, defense costs add up, and lawsuits can take years.

Why the Caps Don’t Cap Your Risk

Many owners hear “about $90,000” and assume their risk ends there. Unfortunately, that is rarely true.

First, lawyers often add other claims to a dram shop suit. A fight may bring a negligent security claim. A fall may bring a premises claim. These claims may not fall under the dram shop caps.

Second, the caps can stack. A busy night can involve several injured people, each with their own limit.

Third, the market is tight. IA Magazine reports rising liquor liability rates and shrinking capacity in 2026. As a result, carriers are pickier about the bars they write.

What Chicago and Other Towns Require

Your local liquor license often sets the floor for your Illinois liquor liability coverage. For example, Chicago asks for a liquor liability or dram shop certificate with each license application. The policy must carry at least $300,000 per occurrence and last the full license period. Also, the Local Liquor Control Commissioner must be the certificate holder, with 30 days’ notice before cancellation. (City of Chicago)

Suburbs and counties set their own rules. So check each town where you hold a license. Meanwhile, landlords and lenders often ask for more. Many leases call for $1 million or more, and some add an umbrella on top.

General Liability Usually Excludes Liquor

Here is a gap we see often. Many owners assume their general liability policy covers alcohol claims. Usually, it does not.

Most standard general liability forms exclude liquor liability for businesses that sell or serve alcohol. Therefore, a bar or restaurant needs a separate liquor liability policy or endorsement. Without it, a dram shop claim may have no coverage at all. For the basics, see our page on general liability insurance.

What a Strong Bar and Restaurant Program Includes

For a growing hospitality group, Illinois liquor liability is only one piece. A complete program often includes:

  • Liquor liability with limits that meet license and lease rules
  • General liability for slips, falls and other premises claims
  • Assault and battery coverage, since many policies exclude or limit fights
  • Umbrella or excess liability that sits over your liquor policy
  • Commercial property, with equipment breakdown and spoilage
  • Business income in case a fire or outage closes you down
  • Workers’ compensation for kitchen and bar staff

Next, check that your umbrella actually covers liquor. Some umbrellas exclude it. Others only follow it if liquor is listed on the schedule of underlying policies. So read the umbrella form, not just the summary page. Learn more on our bars and restaurants insurance page.
Assault and Battery: The Exclusion That Sinks Claims

Fights are one of the most common bar claims. Yet many liquor and general liability policies exclude assault and battery. Others limit it to a small sublimit, well below the main policy limit.

So ask three questions at renewal:

  1. Does the policy cover assault and battery at all?
  2. Is there a sublimit, and how much is it?
  3. Does it cover claims tied to my door staff or security?

If the answers are unclear, get them in writing before you bind.

How Underwriters Price Illinois Liquor Liability

Carriers that want hospitality accounts look closely at how you run your business. In practice, they often ask about:

  • Your mix of food and alcohol sales
  • Your hours, especially late-night closing times
  • Live music, dancing, DJs or cover charges
  • Security staff, cameras and incident logs
  • Server training and ID checks
  • Five years of loss runs

Training matters here too. Illinois requires on-premise servers, and staff who check IDs, to complete BASSET training within 120 days of hire. The card is good for three years. Therefore, keep a current list of every employee’s card. A clean training file helps at renewal and in court.

Steps to Lower Your Dram Shop Risk

Insurance is your backstop. However, your floor staff is your first line of defense. Strong operators tend to share these habits:

  1. Train every server and door person, and track renewal dates
  2. Check IDs every time
  3. Cut off visibly drunk guests, and log it
  4. Offer food and alcohol-free drinks late at night
  5. Keep cameras running, and save footage after any incident
  6. Write up every incident the same night

As a result, you lower the odds of a claim. You also build the records your defense attorney will need. If you own several Chicago locations, our Wicker Park bar insurance page shows how we set up programs by neighborhood.

Illinois Liquor Liability FAQ

Is liquor liability insurance required in Illinois?

In practice, most bars need it to get or renew a license. Local liquor commissions often require proof of coverage. For example, Chicago requires at least $300,000 per occurrence. Landlords usually require it too.

What are the Illinois dram shop limits for 2026?

As of January 20, 2026, the cap is $90,411.55 per person for injury or property damage. The cap for loss of support or society is $110,503. They change every January 20.

Does my general liability policy cover a drunk-driving claim?

Usually not, if you sell or serve alcohol. Most general liability forms exclude liquor liability for these businesses. Instead, you need a separate liquor liability policy.

How much liquor liability should a restaurant group carry?

It depends on your licenses, leases and locations. Many groups carry $1 million per occurrence with an umbrella above it. So start with your strictest lease or license rule.

Do Wisconsin and Indiana follow the same rules?

No. Each state has its own alcohol liability laws. Therefore, a group with locations across state lines needs coverage built for each state.

Get an Illinois Liquor Liability Review

If your group has added locations, your coverage should keep up. We can review your liquor, umbrella and assault and battery wording in one meeting. Then we will show you where the gaps are. Request a commercial quote or call Weer Insurance Group at 773-545-2001.

Read More

Wholesale Distributor Insurance: What Amazon’s New Rules Mean for You

Wholesale distributor insurance just got more urgent. On November 2, 2026, Amazon changes its liability insurance rules for sellers. As a result, many distributors who sell online will need a $1 million policy, even with low sales. At the same time, landlords and retail buyers are asking for more proof of coverage than ever.

At Weer Insurance Group, we see this every week. In fact, two wholesale accounts came to us this month alone. Both had the same problem. They sold products they did not make, yet they carried the risk anyway. So here is what every distributor, importer, and e-commerce wholesaler should know.

What Is Wholesale Distributor Insurance?

Wholesale distributor insurance is not one policy. Instead, it is a package built around how you buy, store, and sell products. Most programs include:

  • General liability with products-completed operations coverage
  • Commercial property for your inventory and equipment
  • Hired and non-owned auto for staff who drive for errands
  • Umbrella or excess liability to raise your limits
  • Product recall for food, candy, and cosmetics
  • Workers’ compensation for warehouse staff
  • Inland marine or cargo for goods in transit

In other words, the right mix depends on what you sell and where it goes. For a closer look at the core policy, see our page on general liability insurance.

Amazon’s November 2, 2026 Insurance Rule

First, the big change. Until now, Amazon required liability coverage only after a seller passed $10,000 in gross proceeds in one month. However, starting November 2, 2026, that threshold goes away for 11 “enhanced safety” categories. These include cosmetics, consumable and ingestible products, children’s products, and lithium battery products, among others.

That means a candy, beauty, or supplement distributor may need coverage no matter how much it sells. Furthermore, the rule applies to existing listings, not just new ones. (My Amazon Guy and EcomCrew have good summaries of the change.)

What Amazon Requires in Your Policy

According to Amazon’s published terms, your policy must have:

  • Commercial general, excess, or umbrella liability coverage
  • $1 million per occurrence and $1 million in total
  • A deductible of $10,000 or less
  • An occurrence-based form that covers every product you list
  • “Amazon.com Services LLC and its affiliates and assignees” as an additional insured
  • A named insured that matches the legal name on your seller account
  • A carrier with worldwide claims handling

Reports say Amazon will give affected sellers 45 days to upload proof. Otherwise, listings in those categories can be turned off. So if you sell in these categories, start now. Underwriting takes time.

Why Distributors Get Sued for Products They Didn’t Make

Many owners assume the maker carries the risk, so they skip wholesale distributor insurance. Unfortunately, that is not how product liability works. When a customer is hurt, every company in the chain can be named in a lawsuit. That includes the maker, the importer, the wholesaler, and the store.

This risk grows when you import. For example, if the factory is overseas, a plaintiff may have no practical way to sue it. As a result, the U.S. importer or distributor often becomes the main target. Markel calls this one of the biggest pitfalls distributors face.

Ask Your Suppliers for a Vendor’s Endorsement

A vendor’s endorsement adds your company to the maker’s product liability policy. Consequently, their insurer may defend you first. Still, it does not replace your own coverage. Endorsements can be narrow, and overseas policies may not respond in U.S. courts.

Occurrence vs. Claims-Made: The Trap Most Buyers Miss

Next, check the policy form. Some carriers offer distributors a claims-made policy, often with high limits at a tempting price. However, product claims can show up years after the sale.

Here is why that matters. A claims-made policy usually starts at a “retroactive date.” If you never had insurance before, that date is the first day of the policy. Therefore, nothing you sold before that day would be covered. On the other hand, an occurrence policy works differently. It covers any injury that happens while the policy is active, even if the claim comes years later.

We saw this firsthand this month. A long-running Chicago distributor with no prior coverage was offered a claims-made option. On paper, it looked fine. In reality, it would have left years of past sales uncovered. So we pushed for an occurrence program instead.

In addition, Amazon and most landlords require occurrence form. Simply put, a cheaper claims-made quote may not even meet your contract.

Wholesale Distributor Insurance for Your Warehouse

Your inventory is often your largest asset. Yet many distributors are underinsured on commercial property. Underwriters will ask about:

  • Building construction and sprinklers (wet, dry, or ESFR)
  • Central-station alarms and cameras
  • Flammable goods, such as alcohol-based perfume, aerosols, or lithium batteries
  • How those goods are stored, and how much you keep on hand
  • Your highest inventory value, including the holiday peak

For instance, inventory that runs $750,000 most of the year may climb to $1 million in the fourth quarter. In that case, a peak-season endorsement can raise your limit for those months. Meanwhile, business income coverage protects your cash flow if a fire or water loss shuts you down.

Lease and Retailer Requirements for Wholesale Distributor Insurance

Often, the first push for coverage comes from a lease or a vendor agreement. Typical requirements include:

  • $1 million / $2 million general liability, with a products-completed operations aggregate
  • Additional insured status for ongoing and completed operations
  • Primary and non-contributory wording
  • Waiver of subrogation on general liability, auto, and workers’ comp
  • An umbrella that follows form over liability, auto, and employers liability
  • Carriers rated “A” or better by AM Best
  • 30 days’ notice of cancellation

Before you sign, send us the insurance section of your lease. That way, we can match the policy to the contract the first time.

Product Recall Coverage for Food, Candy, and Cosmetics

Product liability pays when someone is hurt. By contrast, product recall insurance pays to pull product off the shelves. That can include notices, shipping, disposal, and lost profit. Most general liability policies exclude recall costs.

For food, candy, and cosmetics companies, adding recall to your wholesale distributor insurance is worth pricing. Also, a written recall plan and lot-level tracking can improve your terms.

What Underwriters Will Ask You: A Checklist

To get the best price, have these ready:

  1. Annual revenue, split between wholesale and online sales
  2. A product list by category, with the share of sales for each
  3. The share of goods that are imported, and whether you are the importer of record
  4. Any private-label or repackaged products
  5. Warehouse details: square feet, construction, sprinklers, and alarms
  6. Your normal and peak inventory values
  7. How you store any flammable or hazardous items
  8. Prior insurance and loss history, or a short note on why you had none
  9. The insurance section of your lease and key customer contracts
  10. Your recall plan and lot tracking, if you have them

Above all, answer accurately. A wrong “yes” on an application can cost you coverage after a claim.

What Does Wholesale Distributor Insurance Cost?

Cost depends on what you sell, your revenue, and where it goes. For example, a small distributor of low-risk goods may pay a few thousand dollars a year. However, a large importer of cosmetics, perfume, or food is a different story. Once you add an umbrella and recall, the total can run well into five figures or more. That is why the structure matters as much as the price.

Why Work With an Independent Agency

Distributor risks rarely fit a standard business owner’s policy. As an independent agency, we can shop many carriers at once. That includes standard, surplus lines, and recall markets. As a result, you get one coordinated program instead of a patchwork. We work with wholesalers, importers, and online sellers across Illinois, Wisconsin, and Indiana.

Frequently Asked Questions

Do I need insurance to sell on Amazon?

It depends on your category and sales. Starting November 2, 2026, sellers in 11 enhanced safety categories need a $1 million occurrence policy, regardless of sales. For other categories, coverage is still required after $10,000 in monthly gross proceeds.

Does my manufacturer’s insurance cover me as a distributor?

Only if you are added through a vendor’s endorsement, and even then coverage can be limited. Therefore, you should carry your own product liability coverage.

Is product liability part of general liability?

Usually, yes. Most general liability policies include products-completed operations coverage. However, some policies limit or exclude certain products, so check the details.

Does general liability cover a product recall?

No. Recall costs are typically excluded. Instead, you need a separate product recall policy.

What limits do distributors usually need?

Most start with $1 million / $2 million in general liability. Then, many add a $2 million to $5 million umbrella to meet lease, retailer, or lender requirements.

Get a Wholesale Distributor Insurance Quote

Whether Amazon’s deadline is close or a landlord just asked for a certificate, we can help you move fast. Request a commercial quote or call Weer Insurance Group at 773-545-2001. You can also read our guide on whether delivery drivers need commercial insurance.

Read More

Chicago Plumber Insurance: How to Cut Workers’ Comp Costs

Why Plumbing Carries Big Insurance Risks—And Why It Matters to Your Bottom Line

Chicago plumber insurance comes with some of the toughest challenges in the trades. It’s not just about injuries on the job. It’s about the damage your work can cause if something goes wrong.

A burst pipe. A missed shutoff valve. A ruptured line during installation. Any of these can mean $50,000 in water damage to a customer’s home or office. That’s not a claim. That’s a catastrophe.

Plumbers also work in tight spaces: basements, crawl spaces, and roofs. That means fall risks and back injuries happen every day. It’s why carriers treat plumbing as a higher-risk trade.

Here’s the reality: You need two separate insurance programs. Workers’ compensation covers your crew when someone gets hurt. Commercial auto covers your fleet when an accident happens between jobs. Ignore either one, and a single claim can wipe out your profit for the year.

Let’s break down what you actually need.


Chicago plumber insurance: what your auto policy should include

Your commercial auto program must address three specific risks in plumbing work:

Your service trucks and vans

Your fleet is on the road constantly, between emergency calls, supply runs, and scheduled jobs. So you need comprehensive and collision coverage, plus auto liability and medical payments coverage. In addition, Chicago’s winter weather makes uninsured motorist coverage essential.

Why? Because Chicago drivers don’t always carry adequate insurance. A rear-end collision in your service van costs thousands—not just in vehicle repair, but in lost service days and equipment damage.

Plumbing service van parked on a snowy Chicago street, Chicago plumber insurance

Hired and non-owned auto coverage (HNOA)

Most plumbers miss this one. Here’s the situation: A technician uses their personal pickup to grab supplies from the wholesale distributor. A subcontractor shows up in their own van for emergency work. An accident happens.

Who’s liable? You are.

HNOA coverage protects you when employees or subcontractors use personal vehicles for business. Ask for it explicitly. Many carriers don’t include it automatically. This is one of the most critical gaps we see in plumber policies—don’t be caught without it.

Liability limits that match your market

General contractors and property managers expect plumbing subcontractors to carry $1 million per occurrence liability. If your limit is $500K, you’re either paying out-of-pocket for higher coverage on each bid, or you’re losing jobs.

Check your limits now. It costs just a few dollars more per year to meet the market standard. Why lose a job over this?

See also: What Chicago electrical contractors need to know about commercial auto and workers’ comp. Similar market standards apply across the trades.


What Actually Drives Your Workers’ Comp Cost in Illinois?

Illinois requires workers’ compensation if you have even one employee. Period. It’s mandated under the Illinois Workers’ Compensation Act (820 ILCS 305).

But here’s what most plumbers don’t understand: Your cost isn’t fixed. It’s based on three factors.

Factor 1: Payroll

The more workers you hire, the higher your premium. Workers’ comp is calculated as a percentage of payroll. If your annual payroll jumps from $200,000 to $300,000, your premium goes up. It’s straightforward math.

Factor 2: Your claims history (the e-mod)

This is where it gets interesting.

Carriers assign you an “experience modification factor,” or e-mod. It’s a multiplier. Plumbers with clean records pay close to the base rate—maybe 0.85× (a 15% discount). Plumbers with multiple claims pay a surcharge—maybe 1.15× or 1.25× (a 15–25% increase).

Here’s the kicker: One serious claim affects your rate for three years. A technician scalded by a burst? That’s on your record. A back injury from improper lifting? That follows you.

But on the flip side, a three-year clean record? That discount adds up fast.

Factor 3: Safety practices

Carriers track patterns. Multiple back injuries signal poor lifting protocols. Repeated scalding incidents suggest weak burn protection. Slips in crawl spaces point to missing safety gear. OSHA’s construction safety resources are a good place to start closing those gaps.

When you invest in OSHA-approved plumbing safety training, proper PPE (burn gloves, slip-resistant boots, back support), and confined-space protocols, you don’t just protect your crew. You save thousands in premiums.

Bottom line: Don’t expect a flat fee. Instead, your Chicago plumber insurance cost depends on your payroll, your claims history, and your safety record. That’s why working with an experienced agent who understands plumbing operations matters.


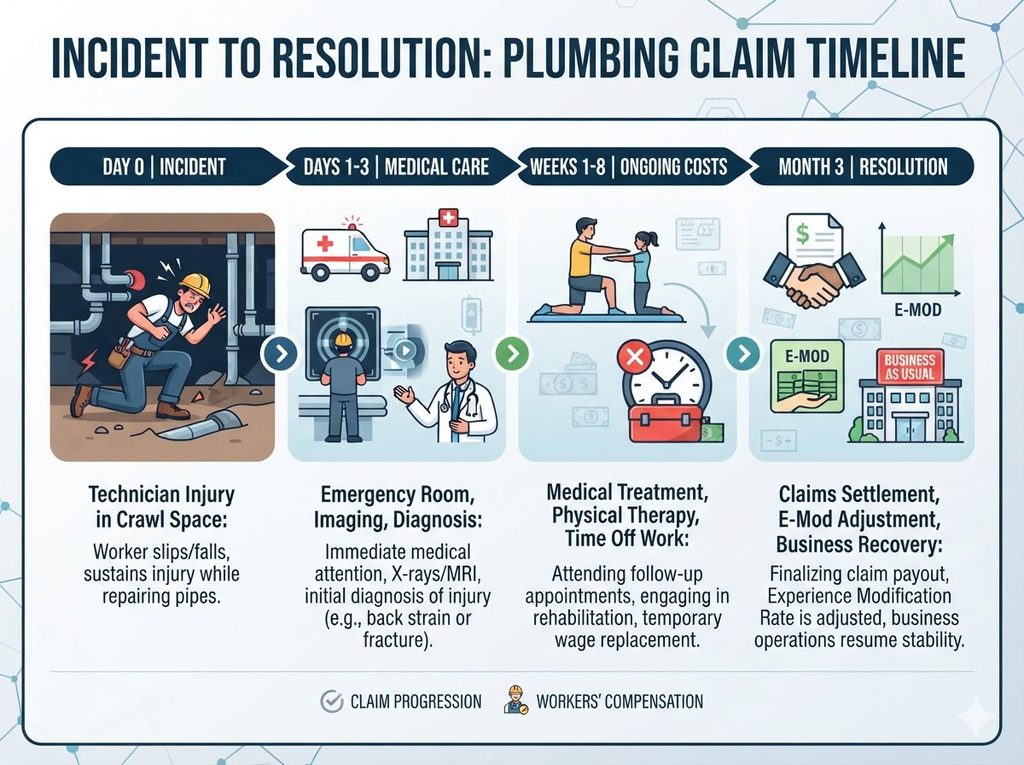
Timeline of a plumbing workers' comp claim from injury to resolution

A Real Claim Story from Chicago

A residential plumbing contractor on the South Side runs a three-person crew. November. Cold snap. He gets called to a residential building with a burst pipe in a crawl space.

One technician works in a stooped position for an hour. Removing the frozen section. Accessing tight spots. Then—sharp pain in his lower back. He can’t straighten up.

Urgent care. MRI. Diagnosis: Herniated disc. Restrictions: No lifting over 10 pounds for six weeks. Physical therapy. Two months off work.

If he didn’t have workers’ comp:

The technician would sue him directly. Medical bills? Out of pocket—$8,000 for imaging and therapy. No paychecks for two months? That comes from the business. With two technicians left, he loses winter emergency calls—peak season for plumbing. Premiums skyrocket at renewal—20%+ increase for three years.

Total damage: Over $40,000 plus lost revenue.

If he had proper coverage:

Workers’ compensation covered everything. The carrier handled the claim. The technician got his wages while recovering. The e-mod adjustment at renewal? Modest. Around 1.05. The business stayed operational.

He also had commercial auto coverage because one technician had been hit earlier that year while parked at a customer’s home. That accident? Handled under the fleet policy. Not a personal claim.

Two separate incidents. Two separate programs. Business survives intact.


Certificates of Insurance: The Paperwork That Stops You From Working

Property managers and general contractors won’t let you start work without a Certificate of Insurance on file.

More than that? Many want it dated within 30 days. Some request updates monthly during long projects.

What does a COI prove? That you’re covered for workers’ comp, general liability, and commercial auto.

What happens without it? You’re off the job site. Mid-project. No exceptions.

What if it’s outdated? You’re shut down. That means the blocked toilet or leaking pipe sits unfixed while you scramble to get your insurance updated.

That’s a relationship killer.

Smart plumbers make this automatic:

First, ask your agent for same-day turnaround on certificates. Some carriers now offer self-service portals where you download them instantly.

Second, request a fresh COI before you think you’ll need it. Build a buffer into your workflow.

In Chicago’s competitive residential market, being the plumber who shows up with paperwork ready is the plumber who gets the repeat call.

See also: What Chicago HVAC contractors need to know about workers’ comp and auto coverage. The same certificate principles apply across trades.

Chicago plumber insurance FAQs

Is workers’ comp required for plumbers in Illinois?

Yes. Illinois requires workers’ comp for almost every employer with even one employee, full- or part-time. Skipping it exposes you to fines, stop-work orders, and lawsuits from injured workers.

What workers’ comp class code do plumbers use?

Most plumbing contractors fall under NCCI class code 5183 (Plumbing NOC and Drivers). Your premium is a rate per $100 of payroll in that code, adjusted by your e-mod. Office staff usually go under clerical code 8810, which costs far less.

Do I need commercial auto if my techs drive their own trucks?

Yes, in most cases. Hired and non-owned auto (HNOA) coverage protects you when employees use personal vehicles for work. If the business owns or leases vans, you need a commercial auto policy as well. Personal auto policies often exclude business use.

How much liability coverage do GCs require from plumbing subs?

Most ask for $1 million per occurrence and $2 million aggregate in general liability, plus $1 million in auto liability. Many also require additional insured status and a waiver of subrogation. Larger commercial jobs often add an umbrella.

Where can I get a Chicago plumber insurance quote?

An independent agency can compare several carriers at once. Have your payroll, vehicle list, and three years of loss history ready. Then call Weer Insurance Group at 773-545-2001 or request a quote online.


How Weer Insurance Group Helps Chicago Plumbers

We’ve spent years building partnerships with 30+ carriers that specialize in trades insurance.

We understand plumbing. We know back injuries and scalding are everyday hazards. We know winter ramps up your revenue and your exposure at the same time. We know Illinois law. And we know that a missing COI can cost you more than the insurance itself.

Whether you’re a solo technician adding your first helper or a growing firm managing multiple service trucks, we build a Chicago plumber insurance program that covers your workers, your fleet, and your reputation.

Ready to lock in your coverage before winter?

Contact us at 773-545-2001, request a quote online, or see our plumber insurance page. You can also learn more about us. Now is the time to make sure your paperwork is current and your coverage is solid.

Read More

Chicago Roofing Contractor Insurance: How to Cut Costs

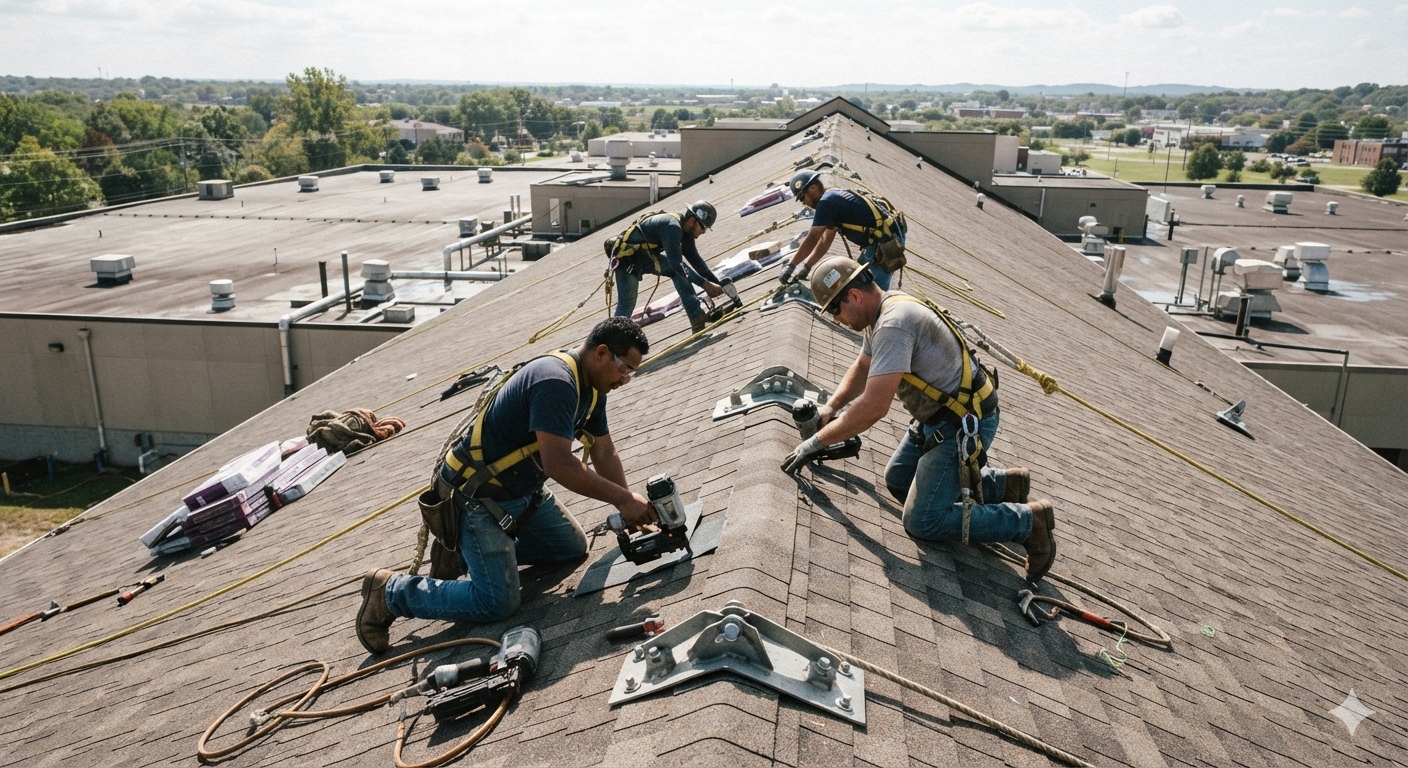
Roofers in fall-protection harnesses on a steep roof, Chicago roofing contractor insurance

Quick answer: Chicago roofing contractor insurance costs more than coverage for almost any other trade. Roofing is the most cited trade in federal OSHA fall-protection enforcement. It also carries one of the three highest workers’ comp rates in construction (NCCI code 5551). Still, roofers who document their safety programs and control their EMR can save thousands a year. Keeping subcontractor certificates current and closing coverage gaps lowers costs even more.

Last updated: October 23, 2026

Why Chicago roofing contractor insurance costs more

Roofing sits at the top of two lists no contractor wants to lead: OSHA enforcement and workers’ comp rates.

Federal OSHA enforcement data shows roofing contractors drew 86.5 citations per 100 inspections in fiscal year 2025. That is the highest rate of any construction trade. Framing came next at 83.5, followed by siding (43.6), plumbing and HVAC (24.2), masonry (20.4), and electrical (19.3). Roofing alone drew more than half of the 5,914 federal fall-protection citations that year. The average penalty was about $7,320 per citation. In fact, fall protection (29 CFR 1926.501) has topped OSHA’s most-cited list for 15 years in a row. Roofing is the biggest reason why.

On the workers’ comp side, NCCI class code 5551 (“Roofing — All Kinds and Drivers”) ranks among the three most expensive codes in construction. Carriers price it high because the loss data supports it. Falls from roofs and ladders cause more severe claims than almost any other construction injury. Long-term disability, multiple surgeries, and wrongful death claims are all more common in roofing. As a result, workers’ compensation is often a roofer’s biggest insurance cost.

Then add Chicago’s weather cycle. Hail and wind claims spike every spring and summer. Next comes a rush of tear-off and re-roof work before winter. So both frequency (how often things go wrong) and severity (how much it costs) work against you at renewal.

What Chicago roofing contractor insurance should include

A complete Chicago roofing contractor insurance program usually has six parts. Skip one, and a small claim can turn into a lawsuit. A gap can also sink a signed contract when a general contractor’s risk manager reviews your certificate of insurance.

  • General liability (GL). Covers injury and property damage to others. Think of a dropped tool that dents a car, or a tear-off that lets rain into a client’s home. Every general contractor and property manager will ask to see your general liability on a certificate before you start work.
  • Workers’ compensation. Illinois requires it for almost every employer with even one employee. Carriers price it mainly on your class code 5551 payroll and your experience modification rate (EMR). For most roofers, it is the largest line in the insurance budget.
  • Commercial auto. Covers the trucks and trailers that haul ladders, shingles, and debris between jobs. A personal auto policy won’t cover a vehicle titled to the business or used mainly for work. It also excludes the tools and materials in the bed. Learn more about commercial auto insurance.

Coverage for tools, large verdicts, and finished roofs

  • Inland marine (equipment coverage). Protects ladders, lifts, nail guns, and other tools that move from site to site. Standard property insurance does not follow your equipment off-premises.
  • Umbrella / excess liability. Sits on top of your general liability, auto, and employers’ liability limits. Jury awards in construction injury cases keep growing. That’s why most brokers now suggest $3–10 million in umbrella limits for roofers doing real commercial volume. The old standard of $1 million in primary GL is no longer enough.
  • Completed operations coverage. A leak that shows up eight months after the job is still your liability. So check your GL policy for a roofing exclusion or a sublimit on completed operations. We find this gap often when we review a roofer’s current policy.

What drives your premium up or down

FactorWhy it matters
Experience modification rate (EMR)The single biggest lever on your workers’ comp premium. An EMR above 1.00 can add tens of thousands of dollars a year; staying at or below 1.00 signals a strong safety record to underwriters.
Residential vs. commercial mixCommercial and multi-family roofing carries different liability exposure than single-family residential work, and carriers price the two differently.
Documented fall protection programWritten procedures, harness and anchor point documentation, and toolbox-talk records give an underwriter something concrete to price against — “we’re careful” is not a rating factor, a program is.
Subcontractor use and their COIsIf you use subs and don’t collect and verify their certificates of insurance, their claims can flow back onto your policy — and your own GL premium reflects that exposure whether or not a sub ever gets hurt.
Payroll, revenue, and years in businessStandard rating factors, but roofing’s severity means small changes here move the needle more than they would in a lower-hazard trade.
Storm/CAT claim historyA book of hail and wind damage repair work brings its own claims pattern that carriers track separately from routine installation work.

The Certificate of Insurance problem that costs roofers bids

Today, every general contractor, property manager, and municipality in the Chicago area screens subcontractor COIs before work starts.

Roofing subs get flagged more often than almost any other trade. In most cases, the problem traces back to how the Chicago roofing contractor insurance policy was set up.

The most common problems we see:

  • Additional insured endorsement missing or worded wrong. Most GC contracts require your GL policy to name the GC as an additional insured. It must also be on a primary and non-contributory basis. A plain certificate holder line isn’t enough.
  • Waiver of subrogation not included. Many commercial contracts and property management agreements require it by name.
  • Excluded operations. Some policies carry a roofing exclusion or a steep-slope or height sublimit. You may not notice it until a claim is denied or a reviewer flags the endorsement.
  • Umbrella limits that don’t match the contract. A $1M/$2M policy with no umbrella rarely wins commercial or multi-family bids in Chicago. Instead, $3–5M in total limits is becoming the baseline ask.

Has a red-flag COI ever held up a bid or cost you one? The fix almost always happens when your agent builds the policy, not when someone requests the certificate. So talk with your agent before your next bid deadline, not after.

Five steps to lower your Chicago roofing contractor insurance costs

  • Pull your EMR and understand what drives it. If it’s above 1.00, ask your agent which claims affect it. Also ask how long they will stay in your experience period.
  • Put your fall protection program in writing. Underwriters price written programs better than verbal ones. A one-page policy, plus a log of harness checks and toolbox talks, is often enough.
  • Audit your subcontractor COI file. Every sub on every job needs a current certificate naming you as additional insured. Add a waiver of subrogation where your contracts require one.
  • Check completed operations and roofing endorsements line by line. Don’t assume a prior carrier’s GL policy covers roofing at full limits. Ask specifically.
  • Match your umbrella limits to your actual contracts. Moving from residential to commercial and multi-family work? Then your umbrella needs have likely grown, even if no one has flagged it yet.

Frequently asked questions

How much does Chicago roofing contractor insurance cost?

It depends on your revenue, payroll, EMR, and mix of residential and commercial work. So no single number fits every roofer. The best way to know is an apples-to-apples comparison against your current program, not a rate you saw online.

Is workers’ compensation required for roofing contractors in Illinois?

Yes. Illinois requires workers’ comp for almost all employers with employees, including sole proprietors with even one worker. Roofing’s class code 5551 is also rated among the highest in construction.

What is an EMR, and why does it matter so much for roofers?

Your experience modification rate (EMR) compares your workers’ comp claims to other companies doing similar work. An EMR of 1.00 is average. Below 1.00 means better claims experience and a lower premium. Above 1.00 means the opposite. Because roofing claims already run high, EMR swings move real dollars.

Do I need an umbrella if I already have $1 million in general liability?

For most roofers doing commercial, multi-family, or municipal work in the Chicago area, yes. Many contracts now require $3–5 million or more in combined limits. A $1 million primary policy alone often won’t meet that.

Why did a general contractor reject my certificate of insurance?

The usual causes are a missing or poorly worded additional insured endorsement, or no waiver of subrogation. A hidden roofing exclusion or height sublimit can also trigger it. So can umbrella limits that fall short of the contract.

Get your Chicago roofing contractor insurance reviewed before your next bid

Weer Insurance Group works with artisan contractors and roofing companies across Chicago, the north and northwest suburbs, Wisconsin, and Indiana. We focus on exactly this kind of review: EMR analysis, additional insured and waiver language, umbrella limits, and sub COI compliance. Has a certificate ever held up one of your bids? Or has it been a while since anyone checked your program against current contracts? Either way, we’re happy to take a look.

See our roofing contractor insurance page, request a quote, or call 773-545-2001. Working through the cold months? Read our guide to builder’s risk insurance for winter construction.

Weer Insurance Group is an independent insurance agency with offices in Chicago and Spring Grove, Illinois, serving contractors throughout Illinois, Wisconsin, and Indiana.


Sources

  • U.S. Occupational Safety and Health Administration (OSHA), federal fall-protection enforcement data, fiscal year 2025
  • National Council on Compensation Insurance (NCCI) classification data, class code 5551 (Roofing — All Kinds and Drivers)
Read More

Chicago HVAC Insurance: How to Cut Workers’ Comp Costs

Why HVAC Work Carries Higher Insurance Risk

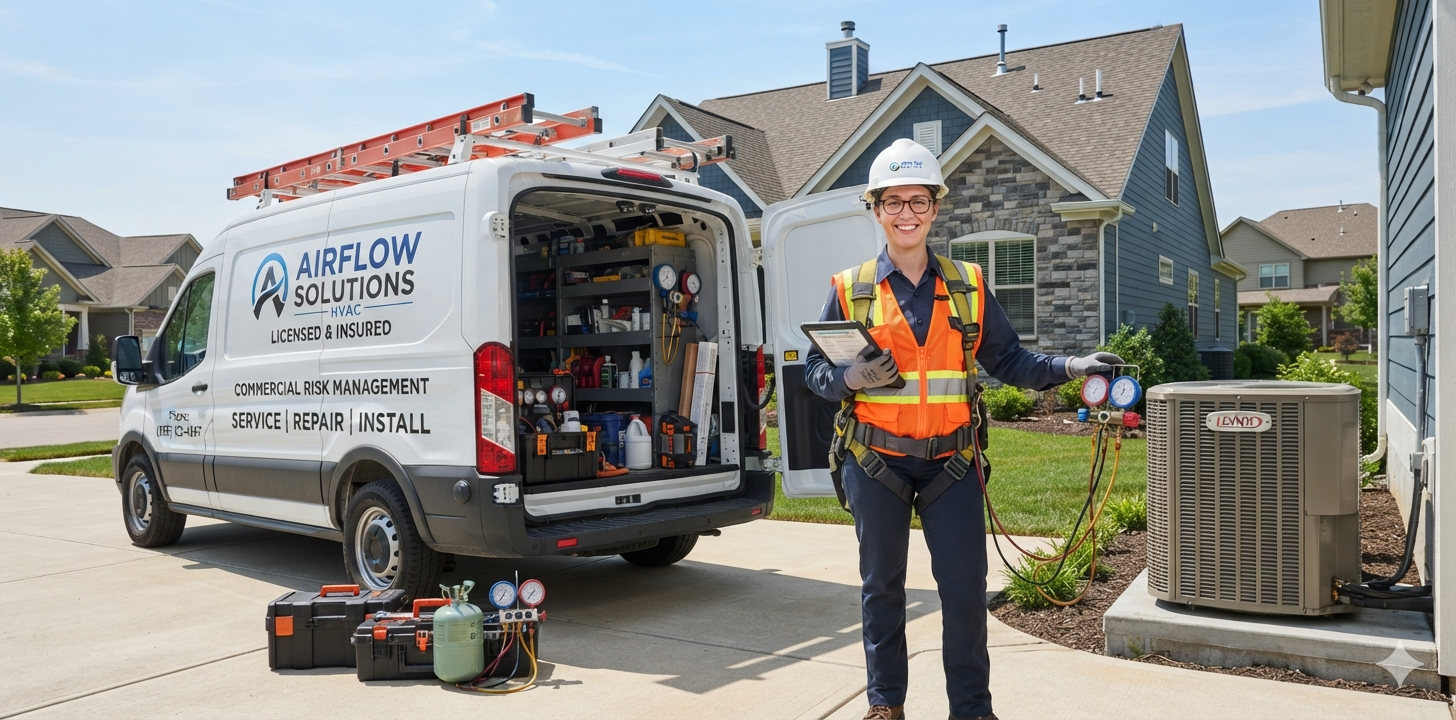
HVAC technician with a service van at a residential job, Chicago HVAC insurance

Chicago HVAC insurance has to account for some of the highest injury risks in the skilled trades. Your crews climb ladders, work on roofs, and move heavy equipment every day.

Falls are everyday hazards. So are furnace burns, refrigerant exposure, and repetitive strain injuries.

However, the insurance picture doesn’t stop at the job site. Your exposure has two critical touch-points:

Workers’ compensation covers your crew when someone gets hurt on a job. That could be a technician burned during a furnace install, a helper who falls off a ladder, or a tech injured while servicing a rooftop unit.

Commercial auto insurance protects your fleet when the risk moves. Your service vans carry expensive tools and equipment between jobs. They need specific coverage, especially if employees or subcontractors also use personal vehicles for work.

Ignore either one, and one bad incident can wipe out a year’s profit or sink your company entirely.

What Should Be in Your Commercial Auto Policy?

Your commercial auto program needs to address three layers of HVAC fleet risk:

Service trucks and vans. Your primary fleet is likely your most valuable and most-driven asset. You need comprehensive and collision coverage (especially if financed), auto liability, and medical payments. In Chicago’s dense urban routes and winter weather, uninsured motorist coverage is essential.

Hired and non-owned auto (HNOA). If a technician uses a personal pickup to grab parts, you can be liable for an accident. The same goes for subcontractors who arrive in their own vans.

HNOA coverage closes that gap. Many policies don’t include it by default, so ask for it explicitly. Then make sure your policy lists your active fleet.

Liability limits that match your market. General contractors routinely require HVAC subcontractors to carry $1 million per occurrence/$2 million aggregate auto liability before stepping onto a commercial site. If your current limits are $500K/$1M, you’re either paying out-of-pocket to bump them up or losing bids. Verify your limits when you quote jobs; it costs just a few dollars more per year to meet the market standard.

What Drives Workers’ Comp Cost for HVAC Contractors in Illinois?

Illinois requires all employers with one or more employees to carry workers’ compensation insurance under the Illinois Workers’ Compensation Act (820 ILCS 305). The state doesn’t set a flat rate. Instead, your cost depends on three main factors:

Payroll. The larger your crew, the higher your premium. Workers’ comp is calculated as a percentage of payroll (the “rate” per $100 of payroll), so adding a technician directly increases your annual cost.

Experience modification factor (e-mod). This is the multiplier that reflects your claims history. Contractors with no or few claims pay close to the state baseline rate. Contractors with multiple injuries or high-cost claims pay a surcharge (e.g., 1.15 or 1.25× the base rate). One serious claim can affect your e-mod for three years. Conversely, a clean record earns a discount (e.g., 0.85×).

Safety practices and incident trends. Even before a claim settles, carriers and risk consultants track which contractors experience recurring incidents. A history of falls, burns, or vehicle accidents signals poor safety culture—and insurers price that risk accordingly. Investing in OSHA-approved training, fall protection equipment, and vehicle maintenance protocols doesn’t just save lives; it saves thousands in premiums over time.

Don’t expect one flat price that fits every HVAC shop. Your Chicago HVAC insurance cost is unique to your payroll, claims history, and underwriting profile. So work with an experienced agent who will request your last three years of payroll and loss history. That’s how you get an accurate quote and find ways to cut costs.

A Real Claim Story

A commercial HVAC contractor in Pilsen with five technicians was called to replace a furnace in a residential property in November. The job involved removing the old unit from a basement and installing a new high-efficiency model on the first floor. One technician was carrying the old furnace down the basement stairs when he slipped on a wet step, fell backward, and fractured his collarbone and several ribs. The injury required emergency room care, two weeks off work, and six months of physical therapy.

Without proper coverage: The technician would have sued the contractor directly, claiming negligence. The company’s medical costs alone ($18,000 for ER and imaging) would come out of pocket. Workers’ comp premiums would spike—likely a surcharge of 25% or more on future renewals for three years. The crew would be short-handed during winter, the busiest season. Total impact: close to $75,000 in direct costs plus lost revenue.

With proper coverage: Workers’ compensation covered all medical and lost-wage benefits. The contractor’s insurance carrier handled the claim, and the business stayed insured. The claim was recorded on the company’s experience record, but the coverage meant no lawsuit, no out-of-pocket medical bills, and the injured technician was protected. The e-mod adjustment at renewal was modest—around 1.08—because the claim was typical for the trade and handled appropriately.

This contractor also carried commercial auto insurance because one of his techs had been rear-ended in the service van earlier that year while heading to a job. That accident was covered under the fleet policy, not dragged into a personal claim. Having both programs meant two separate incidents didn’t compound into a single catastrophic loss.

Certificates of Insurance: The Paperwork That Can Cost You the Job

General contractors managing apartment renovations, office retrofits, and commercial HVAC projects will not let you start work without a Certificate of Insurance (COI) on file. Many require it to be current—dated within 30 days—and some want updates monthly or quarterly during extended projects.

A COI proves to the GC (and their insurer) that you’re covered for workers’ comp, general liability, and commercial auto. Without it, you’re off the job site. With an outdated one, you’re shut down mid-project, which can cost you days and relationships.

Smart HVAC contractors make COI management automatic: ask your agent for same-day or next-day turnaround when you need new certificates. Some carriers now offer self-service portals where you can download certificates instantly. Build a buffer into your workflow—request a fresh COI before you think you’ll need it. In the competitive Chicago market, being the contractor who shows up with paperwork ready is the contractor who gets the repeat call.

Related reading: commercial auto and workers’ comp for Chicago plumbers and what Chicago electrical contractors need to know.

Chicago HVAC insurance FAQs

Where can I get workers’ comp insurance for my HVAC employees?

An independent agency can shop Chicago HVAC insurance across several carriers at once, which matters in a higher-risk trade. Bring your payroll by job type and your last three years of loss history. If no carrier will write you, the Illinois assigned risk plan is the fallback.

Can I get workers’ comp in Chicago with a high e-mod?

Yes. A high experience mod means fewer carriers will compete for your account, and you will pay more. Still, coverage is available. To bring your mod down, put your safety program in writing, start a return-to-work program, and review open claim reserves with your agent.

What workers’ comp class code do HVAC contractors use?

Most HVAC installation, service, and repair work falls under NCCI class code 5537. Office staff usually go under clerical code 8810, which costs far less. Splitting payroll correctly between the two can lower your premium.

Does my personal auto policy cover my service van?

Usually not. Personal policies often exclude vehicles titled to a business or used mainly for work. They also won’t cover the tools and equipment inside. A commercial auto policy, plus HNOA, closes those gaps.

How much liability coverage do general contractors require from HVAC subs?

Most commercial GCs ask for $1 million per occurrence and $2 million aggregate, plus $1 million in auto liability. Many also want additional insured status and a waiver of subrogation. Larger projects often require an umbrella on top.

How Weer Insurance Group Helps Chicago HVAC Contractors

Weer Insurance Group has spent years building partnerships with 30+ carriers that specialize in trades insurance. We match your business profile—your payroll, fleet size, claims history, and growth plans—to the right program so you get the coverage you actually need at a competitive rate.

Unlike a one-size-fits-all online quote, we spend time understanding HVAC work. We know that fall protection and burn injuries are industry-standard risks. We know that your winter season ramps up in September and peaks in December. We know Illinois law. And we know that a missing COI or an outdated certificate can cost you more than the insurance itself.

Whether you’re a solo technician ramping up to a five-person crew or a growing firm heading into fall, we’ll build a program that covers your workers, your fleet, and your reputation.

Ready to get a quote or talk through your coverage gaps? Call us at 773-545-2001, request a quote online, or see our HVAC contractor insurance page. If you’re heading into heating season, now is the time to lock in your coverage and make sure your paperwork is current.


Sources: Illinois Workers’ Compensation Act (820 ILCS 305); NCCI classification data. Example claim scenarios are composites based on typical incidents and do not represent any single business or individual. Actual claim costs and outcomes vary by circumstance, coverage limits, and carrier.

Read More

Chicago Electrician Insurance: Workers’ Comp Made Simple

Electrician testing a panel at a commercial build-out, Chicago electrician insurance

Why Electrical Work Carries Higher Insurance Risk

Electrocution is one of the “Fatal Four” leading causes of construction worker deaths, along with falls, struck-by, and caught-in/between hazards (OSHA). For that reason, Chicago electrician insurance has to cover your risk in two places. First, a workers’ comp policy priced for real injury exposure. Second, a commercial auto policy for the vans and trucks your crews live out of between jobs.

Chicago electrician insurance: what your auto policy needs

Your commercial auto policy should cover three things:

  • Owned vehicles: Service vans and trucks carrying tools, ladders, and testing equipment need auto liability plus a contractors’ equipment floater — one without the other leaves a gap.
  • Hired & non-owned auto (HNOA): If employees or subs ever drive a personal vehicle to a job site, or you rent a vehicle for a bigger project, HNOA coverage closes a gap most electricians don’t discover until a claim happens.
  • Higher liability limits: Many general contractors now require $1M/$2M auto liability limits before an electrical sub can even step onto a job site — more on that below.

What Drives Workers’ Comp Cost for Electricians in Illinois?

Illinois law requires nearly every employer with employees to carry workers’ compensation, even a one-person shop with a single helper (Illinois Workers’ Compensation Act, 820 ILCS 305). That’s true whether workers are full- or part-time. For electricians, your premium comes down to three things:

  • Payroll within your electrical work classification code
  • Your experience modification factor (e-mod) — your claims history moves this up or down every year
  • Safety practices — a single injury claim can raise your e-mod for up to three years

Rather than quote one number that won’t hold true for every shop, here’s the honest answer. Chicago electrician insurance pricing depends on your payroll and loss history, run against current rates for your class code. So bring both to an agent. If a quote sounds too good, or too generic, to be true, it usually is.

Electrician workers’ comp class codes in Illinois

Most electrical contractors fall under NCCI class code 5190 (Electrical Wiring, Within Buildings, and Drivers). Your rate applies per $100 of payroll in that code. Office staff who never visit job sites usually belong in clerical code 8810, which costs far less. Getting that split right is one of the easiest ways to keep your premium in line.

However, some work can fall under other codes, such as outdoor line work. So describe your actual operations to your agent instead of accepting a default code.

Workers’ comp for EV charger installers

EV charger installation is a fast-growing line of work for Chicago electricians. In most cases, it is rated as standard electrical wiring work. Still, tell your agent if you do trenching, pole work, or commercial charging stations. Those jobs can change your class codes, your liability exposure, and the limits property owners require.

Also, if a contract asks for “excess” coverage, it usually means an umbrella over your employers’ liability, auto, and general liability limits.

A $38,000 Wake-Up Call

One of our electrical contractor clients was three weeks into a Chicago Loop tenant build-out when a first-year apprentice fell from a ladder while running conduit, injuring his shoulder badly enough to require surgery. Because the contractor carried workers’ comp coverage matched to his actual payroll and class code, the claim covered roughly $38,000 in medical bills and lost wages — with no out-of-pocket exposure and no work stoppage. The general contractor’s subcontractor agreement also required $1M in commercial auto liability, which the client already carried, so there was no scramble to add coverage mid-project.

Certificates of Insurance: The Paperwork That Can Cost You the Job

Most general contractors won’t let an electrical sub onto a site without a certificate of insurance (COI) showing specific liability, auto, and workers’ comp limits — often naming the GC as an additional insured. A missing or outdated COI is one of the most common, and most avoidable, reasons subcontractors lose bids or get pulled off jobs mid-project. Keep your COI current, and ask your agent for same-day turnaround whenever a GC’s requirements change.

Chicago electrician insurance FAQs

Is workers’ comp required for electricians in Illinois?

Yes. Illinois requires workers’ comp for almost every employer with even one employee. Skipping it exposes you to fines, stop-work orders, and lawsuits from injured workers.

What is the workers’ comp class code for electricians?

Most electrical contractors use NCCI class code 5190. Clerical staff usually go under code 8810. Your agent should confirm the right codes based on the work your crews actually do.

Does commercial auto cover the tools in my van?

Usually not. Commercial auto covers the vehicle and your liability on the road. Tools, testers, and ladders need a contractors’ equipment (inland marine) floater.

What limits do general contractors require from electrical subs?

Most commercial GCs ask for $1 million per occurrence and $2 million aggregate in general liability, plus $1 million in auto liability. Many also want additional insured status and a waiver of subrogation. Bigger projects often add an umbrella.

Where can I get workers’ comp for my electrical employees?

An independent agency can compare several carriers at once. Bring your payroll by job type and three years of loss history. If no carrier will write you, the Illinois assigned risk plan is the fallback.

Related reading: insurance for Chicago plumbers, insurance for Chicago HVAC contractors, and Chicago roofing contractor insurance.

How Weer Insurance Group Helps Illinois Electrical Contractors

We work with 30+ carriers, so we can match your Chicago electrician insurance to your actual payroll, claims history, and fleet. We also turn around certificates of insurance fast when a general contractor needs one. If you’re bidding new work, request a quote, see our electrician insurance page, or call us at 773-545-2001.

Sources: OSHA construction “Fatal Four” hazards; Illinois Workers’ Compensation Act, 820 ILCS 305; NCCI classification data. The client scenario above is a composite example used for illustration.

Read More

Warning: The Hidden Illinois Condo Loophole That Could Cost You Thousands

Published July 15, 2026 | Weer Insurance Group

A pipe bursts inside a shared wall on the fourth floor. Water runs down through three units and into the hallway below. The association’s master policy pays for the repair. But the policy carries a $50,000 deductible, and someone has to cover that cost. Under Illinois law, that someone can be the unit owner whose unit the water came from. Most owners have no idea this is legal until an assessment notice shows up in the mail.

This is exactly the scenario loss assessment coverage is built for. It’s also one of the most misunderstood parts of Illinois condo insurance. Boards often assume the master policy handles everything. Owners often assume their monthly dues already cover it. Neither assumption holds up under 765 ILCS 605/12, and that gap is where associations and owners get hurt financially.

What Does the Illinois Condominium Property Act Require?

Section 12 of the Illinois Condominium Property Act sets the baseline for every condo master policy in the state. The statute requires property insurance on the common elements and the units themselves, including limited common elements. Coverage must be written at replacement cost, not actual cash value, and it must be enough to rebuild to current building code. That’s the foundation every Illinois association must carry.

But the statute doesn’t stop at what the policy covers. Subsection (c) addresses the deductible, and this is the part most owners never read:

The board of directors may, in the case of a claim for damage to a unit or the common elements: (i) pay the deductible as a common expense, (ii) after notice and an opportunity for a hearing, assess the deductible against the owner who caused the damage or from whose unit the damage originated, or (iii) require the affected unit owners to pay the deductible.

In plain terms, the board has three options. Two of those options put the deductible on one owner’s shoulders, not on the association’s shared budget. So a board isn’t required to spread a deductible across every owner through regular dues. Instead, it can legally send the bill to whoever’s unit the damage started in.

Illinois Courts Have Backed This Up

This isn’t just a theory about how the statute might work. In one Illinois appellate court case, a board assessed a deductible back to an owner after a fire that started in that owner’s unit. The owner pushed back on two grounds. First, he argued the association never adopted the statute’s language into its own governing documents. Second, he claimed the insurance payout may have covered the loss, so the deductible didn’t actually cost the association anything.

The court rejected both arguments. It held that 765 ILCS 605/12(c) gives the board this authority directly. The association doesn’t need to copy the statute into its bylaws word for word for it to apply. The court also found that an unreimbursed deductible is, by definition, a cost the policy didn’t cover. Because the board followed the required notice and hearing process, the assessment stood.

The lesson for boards and owners is the same either way: this authority is real, and it has already been tested in court.

Where the Master Policy Stops and Your Personal Coverage Starts

Illinois associations must insure the common elements and, generally, the units themselves. But under the statute, “the unit” usually means the bare walls, floors, and ceilings, not everything inside them. Flooring, cabinetry, owner-installed fixtures, personal belongings, and other interior improvements are excluded from the master policy’s baseline requirement, unless the board has separately chosen to cover them.

That’s exactly the gap a personal HO-6 condo policy is built to fill. A well-structured HO-6 policy covers:

  • Personal property and interior improvements not covered by the master policy
  • Personal liability if someone is injured inside the unit
  • Loss of use coverage if the unit becomes temporarily uninhabitable
  • Loss assessment coverage, which reimburses the owner if the association bills them for a deductible or special assessment tied to an insured loss

That last item is the one most owners skip or underinsure. Given what 605/12(c) allows a board to do, it’s also the item that matters most.

Why a $1,000 Loss Assessment Limit Isn’t Enough Anymore

Standard HO-6 policies often default to a modest loss assessment limit, sometimes as low as $1,000. That number made sense years ago, when master policy deductibles ran a few hundred dollars. But it no longer reflects where the Illinois market has moved.

Rising reinsurance costs, more frequent water and wind losses, and tighter underwriting have pushed many Illinois condo master policy deductibles up to $10,000, $25,000, or even $100,000 in some buildings, especially for wind and hail. If a board assesses that deductible to the unit where the damage started, and that owner’s loss assessment limit tops out at $1,000, the owner covers the rest personally.

Before renewing a personal policy, ask your board or property manager two questions: What is the master policy’s current deductible? And does the board typically charge deductibles back to at-fault owners, or spread them as a common expense? Both answers change how much loss assessment coverage actually makes sense for you.

What Boards Should Tell Owners Before a Claim Happens

Boards that handle this well don’t wait for a claim to explain how deductibles work. Instead, they put the policy in writing ahead of time, in the annual meeting notice, the new-owner welcome packet, or a short insurance FAQ posted with the budget. A board that documents its deductible-assessment policy early, and follows its own notice-and-hearing process consistently, stands in a much stronger position than one that improvises after a loss.

This also protects the board from a separate risk. An owner who feels blindsided by a five-figure assessment has a more sympathetic story to tell a judge or an attorney than one who was told clearly, years in advance, exactly how the association handles deductibles.

The Bottom Line for Illinois Condo Owners and Boards

765 ILCS 605/12 gives Illinois condo boards real flexibility in how they handle master policy deductibles. Courts have consistently upheld a board’s right to bill an at-fault owner directly. For owners, that means loss assessment coverage isn’t optional. It’s the piece of a personal condo policy that stands between a covered loss and a five-figure bill with your name on it. For boards, it means the deductible-assessment policy belongs in writing, communicated well before a claim, not explained for the first time in a hearing notice.

If you’re a board member reviewing your master policy’s deductible structure, or a unit owner unsure whether your HO-6 loss assessment limit is high enough, we can review both sides of the coverage together. That way, there’s no gap between what the association carries and what you’re personally protected for.

Have questions about your condo association’s insurance program or your own HO-6 policy? Contact Weer Insurance Group for a coverage review, or call us at 773-545-2001.


Related Reading

Read More