 Click to Call
 Send us a Text
 Get Directions
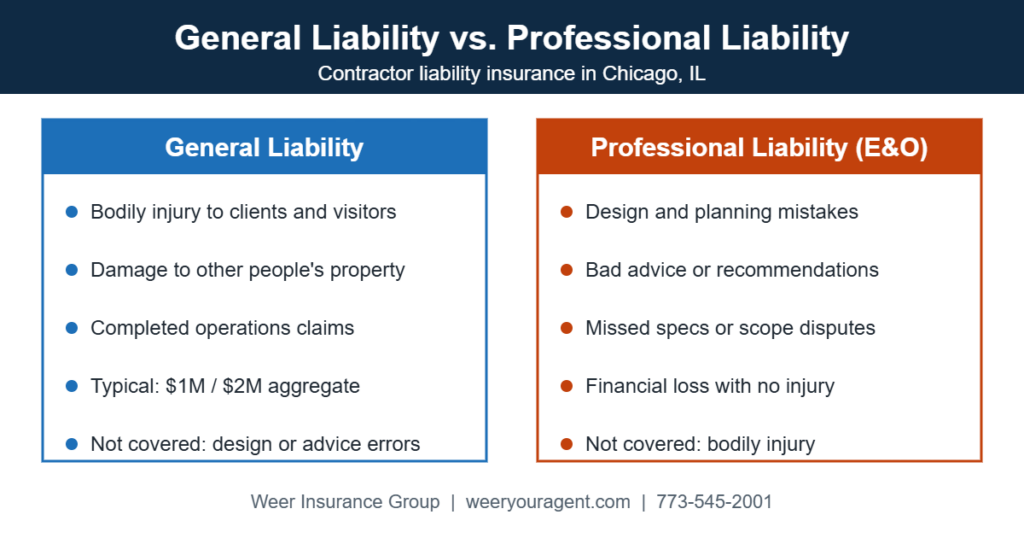
Quick answer: Most contractor liability insurance in Chicago starts with general liability, which covers injuries and property damage you cause to others. However, general liability does not cover mistakes in design, planning, or advice. If you give design input, recommend materials, or take on design-build work, you likely need professional liability too.
What general liability covers for Chicago contractors
General liability is the policy every general contractor, owner, and property manager will ask to see on your certificate of insurance. It responds to physical harm and physical damage. For example:
- A client trips over materials and gets hurt
- A dropped tool injures someone nearby
- A pipe you are working on bursts and floods the unit below
- A ladder scratches a client’s hardwood floor
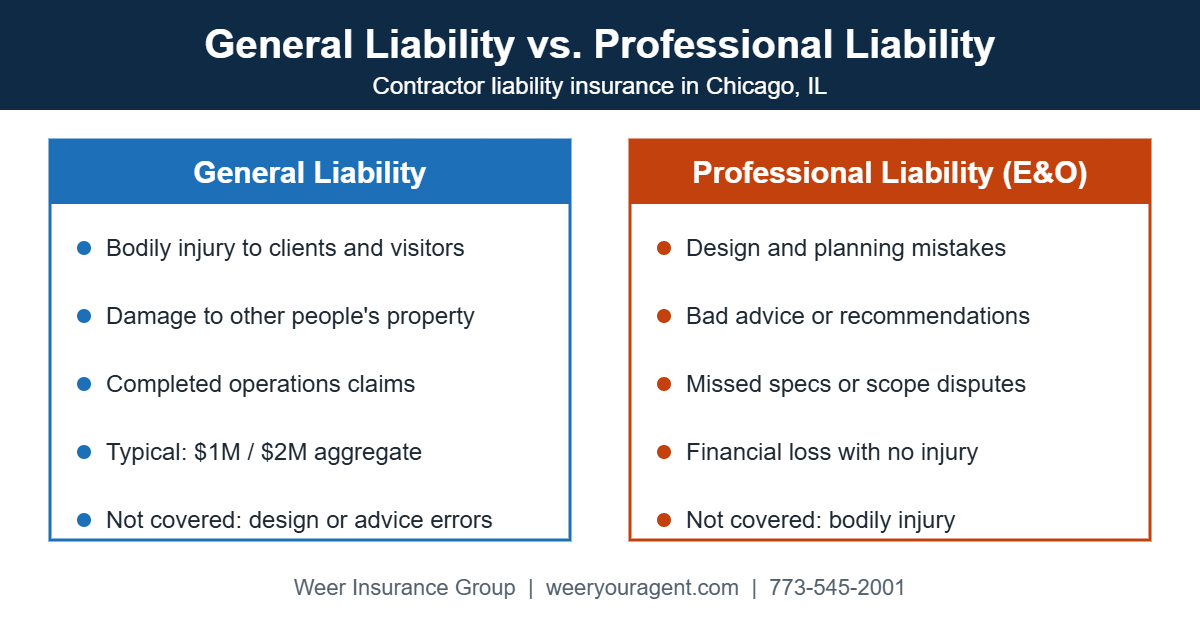
It also includes completed operations coverage. That protects you when damage shows up after a job is finished. Most Chicago contracts ask for $1 million per occurrence and $2 million aggregate.
What general liability does not cover matters just as much. It generally won’t pay to redo your own faulty work. It won’t cover injuries to your own employees, because that’s what workers’ compensation is for. And it won’t respond to claims about bad advice or design errors.
What professional liability covers
Professional liability, also called errors and omissions (E&O), covers claims tied to your judgment or advice rather than physical harm. Say you recommend a material or design approach that later fails. Or a client says the finished project doesn’t match the specs they believed you promised. Those are professional liability claims, not general liability ones.
General liability vs. professional liability at a glance
| General liability | Professional liability | |
|---|---|---|
| Covers | Bodily injury and property damage to others | Financial loss from your advice, design, or planning errors |
| Typical claim | A client trips over materials; a tool damages a floor | A recommended design fails; a measurement error forces rework |
| Who asks for it | Almost every GC, owner, and property manager | Design-build owners, developers, and larger commercial clients |
| Common limits | $1M per occurrence / $2M aggregate | Often $1M per claim, set by contract |
Real scenarios where the difference matters
- A design-build contractor recommends a structural approach that later needs costly rework
- A client claims a renovation didn’t match the agreed scope or specifications
- A plan or measurement error forces a major correction
- A client alleges financial loss from delays caused by planning mistakes, with no physical damage at all
In each case, no one was hurt and nothing was physically damaged. As a result, a general liability policy would likely deny the claim.
Who needs professional liability on top of general liability
Contractors who only perform labor to plans drawn by an architect or engineer may not need it. In contrast, you should consider professional liability if you:
- Offer design-build services
- Prepare drawings, layouts, or measurements that others rely on
- Recommend specific materials, systems, or equipment
- Manage projects or schedules for owners
- Act as a construction manager or owner’s representative
This is increasingly common among Chicago contractors handling complex renovations and commercial build-outs.
Contractor liability insurance requirements in Illinois
Illinois does not set one statewide general liability requirement for every contractor. Instead, the requirements usually come from three places. First, local licensing: the City of Chicago, for example, requires licensed general contractors to show proof of liability insurance. Second, your contracts, which often spell out limits, additional insured status, and a waiver of subrogation. Third, state law for employees, since the Illinois Workers’ Compensation Act requires coverage for nearly every employer.
So before you bid, read the insurance section of the contract. Then make sure your contractor liability insurance in Chicago actually matches it.
What contractor liability insurance costs in Chicago
Cost depends on your trade, revenue, payroll, claims history, and the type of work you do. A small remodeling crew and a commercial design-build firm will pay very different amounts. Professional liability is usually priced separately, based on your design revenue and the size of your projects. The best way to know your number is to have an agent quote both policies side by side.
Frequently asked questions
What liability insurance does a contractor need in Illinois?
Most contractors carry general liability, commercial auto, and workers’ comp if they have employees. Contractors who give design input or advice should add professional liability. Your contracts and local licensing rules set the minimum limits.
Does general liability cover faulty workmanship?
Generally, no. General liability usually won’t pay to fix your own work. However, it can cover damage your faulty work causes to other property, such as water damage from a failed pipe.
Is professional liability the same as E&O insurance?
Yes. Professional liability and errors and omissions (E&O) are two names for the same type of coverage.
Does general liability cover injuries to my own workers?
No. Injuries to your employees fall under workers’ compensation. General liability covers bodily injury to third parties, such as clients, visitors, or other trades on site.
How much liability coverage do Chicago contractors usually carry?
Most carry $1 million per occurrence and $2 million aggregate in general liability. Many commercial contracts also require an umbrella of $2 million to $5 million or more on top.
Get your contractor liability insurance in Chicago reviewed
Weer Insurance Group helps Chicago contractors decide whether their work calls for professional liability alongside general liability and workers’ comp. As an independent agency, we can quote both from multiple carriers. Request a quote, visit our general contractor insurance page, or call 773-545-2001.
Related reading: contractor insurance requirements in the Chicago Loop, Chicago roofing contractor insurance, and builder’s risk insurance for winter construction.